Market commentary | November 16th, 2026

Market commentary | November 16th, 2026

Weekly Market Commentary

November 16th, 2026

Week in Review

This week’s economic data presented a mixed picture, with consumer inflation coming in somewhat hotter than expected while producer price growth moderated. Existing home sales declined, initial jobless claims increased, and longer-term Treasury auction yields moved lower from their prior levels.

Tuesday’s inflation data came in above expectations. October core Consumer Price Index (CPI) increased 0.3% month over month, above the 0.2% forecast and matching the prior month’s increase. Headline CPI rose 0.4%, also exceeding the 0.3% forecast, although the monthly increase slowed from the prior 0.6% reading. Taken together, the results showed consumer-level inflation remaining persistent, with both headline and core prices increasing more than anticipated. Treasury yields moved lower at auction, with the 10-year note clearing at 5.020%, down from 5.300% at the prior auction.

Thursday’s data showed softer existing home sales and an increase in weekly jobless claims. Initial claims rose to 200,000 from 191,000, exceeding expectations of 194,000. Existing home sales declined to an annualized rate of 3.75 million in October, below both the 3.89 million forecast and the prior reading of 3.97 million, pointing to softer resale activity during the month.

Energy markets were also in focus, with crude oil inventories increasing by 4.657 million barrels, a sharp reversal from the prior week’s 865,000-barrel decline and well above expectations for a 600,000-barrel draw. Meanwhile, the 30-year Treasury bond auction cleared at 5.441%, down from 5.618% previously. Combined with the lower 10-year auction yield earlier in the week, longer-term Treasury auction yields declined from their prior offerings despite the hotter-than-expected CPI readings.

Friday’s producer price data offered a contrast to the CPI report. The October Producer Price Index (PPI) increased 0.3% month over month, below the 0.4% forecast and substantially slower than the prior month’s 1.4% increase.

Overall, the week presented a mixed inflation picture, with consumer prices rising more than expected while producer price growth moderated. Alongside softer existing home sales and higher initial jobless claims, the week’s reports showed some moderation in housing and weekly labor market data, even as consumer-level inflation remained an important area to monitor.

Economic and Capital Markets Dashboard

Broad Market Indices 1-week 1-month 3-month YTD
Stock Market (Total Return)
S&P 500 2.54% -3.05% -2.77% 11.54%
Dow Jones 30 2.13% 1.40% -2.38% 10.36%
NASDAQ 2.28% -7.57% -6.08% 8.68%
Russell 1000 Growth 2.83% -9.59% -8.45% -2.46%
Russell 1000 Value 2.29% 3.49% 2.19% 26.71%
Russell 2000 1.36% 0.34% -8.29% 13.57%
Wilshire 5000 2.53% -2.62% -3.10% 11.64%
MSCI EAFE Index 3.27% 1.72% -1.34% 14.37%
MSCI Emerging Market Index 3.34% -5.68% -8.06% 13.53%
VIX -24.73% 26.39% 31.92% 29.10%
FTSE NAREIT All Equity REITs 0.87% 5.81% -0.56% 16.17%
S&P U.S. Aggregate Bond Index -1.32% 0.64% -1.45% -1.11%
Interest Rates 11/13/2026 11/6/2026 10/30/2026 10/23/2026
3-month T-bill Yield (%) 4.22 4.10 4.07 4.14
10-year Treasury Yield (%) 5.16 4.86 4.91 5.00
10Y-2Y Treasury Spread (%) 0.28 0.34 0.34 0.31
30-year Fixed Mortgage Rate (%) 7.23 7.28 7.36 7.43
Commodities
WTI Crude ($/bl) 92.30 94.37 107.56 109.72
Gold ($/Troy Oz) 3,890.85 4,049.60 3,913.25 4,013.30
Bitcoin 68,182.66 75,866.15 77,172.72 81,035.33
Weekly Indicators 11/13/2026 11/6/2026 10/30/2026 10/23/2026
Employment
Initial Unemployment Claims (000’s) – 200.00 191.00 195.00
Quarterly Data 9/30/2026 6/30/2026 3/31/2026 12/31/2025
Output
Real GDP Growth (%q/q, saar) 3.40 2.20 2.50 0.20
Private Consumption (%q/q, saar) 3.80 3.80 0.70 1.90
Monthly Indicators 10/30/2026 9/30/2026 8/31/2026 7/31/2026
Consumption
Consumer Expenditures (%m/m, sa) – 0.51 0.87 0.23
Retail Sales (%m/m, sa) – 0.72 1.28 -0.55
Personal Savings Rate (%) – 3.80 4.00 4.50
Labor
Civilian Unemployment Rate (%) 4.10 4.20 4.10 4.10
Nonfarm Employment (Chg, 000’s) 165 60 186 -10
Real Average Hourly Earnings (%y/y) – -0.33 0.01 -0.02
JOLTS Job Openings (000’s) – 7523 7190 7335
Inflation
Consumer Price Index (CPI) (%m/m, sa) 0.35 0.65 0.40 0.07
Core CPI (%m/m, sa) 0.30 0.33 0.29 0.22
Producer Price Index (PPI) (%m/m, sa) 0.35 1.41 0.41 0.10
Core PPI (%m/m, sa) 0.55 0.28 0.38 0.21
Personal Consumption Expenditures (PCE) (%m/m, sa) – 0.49 0.32 0.06
Core PCE (%m/m, sa) – 0.32 0.26 0.14
Output and Capacity
Industrial Production (%m/m, sa) – 0.66 0.06 0.23
Mfg New Orders (%m/m, sa) – 1.84 0.33 0.77
Durable New Orders (%m/m, sa) – 1.91 0.14 0.87
Durable Inventories (%m/m, sa) – 0.34 0.53 0.47
Survey Data and Composite Indicators
Consumer Confidence (CB, 1985=100) 91.70 84.20 88.60 90.20
ISM Manufacturing Report (%) 55.50 54.50 54.60 55.60
ISM Non-Manufacturing Report (%) 54.50 54.90 55.40 54.10
Leading Economic Index (%m/m) – 0.00 -0.10 0.30
Housing and Construction
Building Permits (Mil. of Units, saar) – 1.40 1.40 1.43
Housing Starts (Mil. of Units, saar) – 1.22 1.29 1.37
New Home Sales (Mil. of Units, saar) – 0.68 0.68 0.65

Week Ahead…

Next week’s economic calendar will be relatively concentrated, with consumer spending data and Federal Reserve communications providing investors with additional perspective on the U.S. economic outlook.

Consumer spending will be a key focus Tuesday, with the release of October retail sales. Headline retail sales are expected to increase 0.2% month over month, slowing from the prior month’s 0.8% increase, while core retail sales are forecast to rise 0.4% after increasing 0.9% previously. The reports should provide an updated look at the strength of consumer demand entering the fourth quarter and whether spending momentum has moderated following the stronger prior-month readings.

Federal Reserve communications will also be in focus. Fed Governor Warsh is scheduled to speak Monday, while Wednesday’s release of the Federal Open Market Committee (FOMC) meeting minutes should provide additional detail on policymakers’ views of economic conditions and monetary policy. Investors will likely look to the minutes for further context on the Fed’s assessment of inflation, economic activity, and the appropriate path for interest rates.

Thursday’s data will provide updates on both the labor and manufacturing sectors. Initial jobless claims are expected to come in at 199,000, little changed from the prior week’s 200,000 reading. Meanwhile, the Philadelphia Fed Manufacturing Index is forecast to decline to 19.2 in November from 20.9 previously, providing another indication of how manufacturing conditions are evolving.

Crude oil inventory data are due Wednesday following the prior week’s 4.657 million-barrel increase, providing another look at near-term supply and inventory conditions in the energy market.

Overall, the week should offer a useful update on the strength of consumer spending and labor market conditions, while the FOMC minutes and Fed commentary could provide additional insight into the monetary policy outlook.

Economic Indicators

  1. CPI: Consumer Price Index measures the average change in prices paid by consumers for goods and services over time. Source: Bureau of Labor Statistics.
  2. Core CPI: Core Consumer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  3. PPI: Producer Price Index measures the average change in selling prices received by domestic producers for their output. Source: Bureau of Labor Statistics.
  4. Core PPI: Core Producer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  5. PCE: Personal Consumption Expenditures measure the average change in prices paid by consumers for goods and services. Source: Bureau of Economic Analysis.
  6. Core PCE: Core Personal Consumption Expenditures exclude food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Economic Analysis.
  7. Industrial Production: Measures the output of the industrial sector, including manufacturing, mining, and utilities. Source: Federal Reserve.
  8. Mfg New Orders: Measures the value of new orders placed with manufacturers for durable and non-durable goods. Source: Census Bureau.
  9. Durable New Orders: Measures the value of new orders placed with manufacturers of durable goods. Source: Census Bureau.
  10. Durable Inventories: Measures the value of inventories held by manufacturers for durable goods. Source: Census Bureau.
  11. Consumer Confidence (CB, 1985=100): Measures the degree of optimism that consumers feel about the overall state of the economy and their personal financial situation. Source: Conference Board.
  12. ISM Manufacturing Report: Measures the economic health of the manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  13. ISM Non-Manufacturing Report: Measures the economic health of the non-manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  14. Leading Economic Index: Measures overall economic activity and predicts future economic trends. Source: Conference Board.
  15. Building Permits (Mil. of Units, saar): Measures the number of new residential building permits issued. Source: Census Bureau.
  16. Housing Starts (Mil. of Units, saar): Measures the number of new residential construction projects that have begun. Source: Census Bureau.
  17. New Home Sales (Mil. of Units, saar): Measures the number of newly constructed homes sold. Source: Census Bureau.
  18. SA: Seasonally adjusted.
  19. SAAR: Seasonally adjusted annual rate.

Market Indices & Indicators:

  1. S&P 500: A market-capitalization-weighted index of 500 leading publicly traded companies in the U.S., widely regarded as one of the best gauges of large U.S. stocks and the stock market overall.
  2. Dow Jones 30: Also known as the Dow Jones Industrial Average, it tracks the share price performance of 30 large, publicly traded U.S. companies, serving as a barometer of the stock market and economy.
  3. NASDAQ: The world’s first electronic stock exchange, primarily listing technology giants and operating 29 markets globally.
  4. Russell 1000 Growth: Measures the performance of large-cap growth segment of the U.S. equity universe, including companies with higher price-to-book ratios and growth metrics.
  5. Russell 1000 Value: Measures the performance of large-cap value segment of the U.S. equity universe, including companies with lower price-to-book ratios and growth metrics.
  6. Russell 2000: A market index composed of 2,000 small-cap companies, widely used as a benchmark for small-cap mutual funds.
  7. Wilshire 5000: A market-capitalization-weighted index capturing the performance of all American stocks actively traded in the U.S., representing the broadest measure of the U.S. stock market.
  8. MSCI EAFE Index: An equity index capturing large and mid-cap representation across developed markets countries around the world, excluding the U.S. and Canada.
  9. MSCI Emerging Market Index: Captures large and mid-cap representation across emerging markets countries, covering approximately 85% of the free float-adjusted market capitalization in each country.
  10. VIX: The CBOE Volatility Index measures the market’s expectations for volatility over the coming 30 days, often referred to as the “fear gauge.”
  11. FTSE NAREIT All Equity REITs: Measures the performance of all publicly traded equity real estate investment trusts (REITs) listed in the U.S., excluding mortgage REITs.
  12. S&P U.S. Aggregate Bond Index: Represents the performance of the U.S. investment-grade bond market, including government, corporate, mortgage-backed, and asset-backed securities.
  13. 3-Month T-bill Yield (%): The yield on U.S. Treasury bills with a maturity of three months, reflecting short-term interest rates.
  14. 10-Year Treasury Yield (%): The yield on U.S. Treasury bonds with a maturity of ten years, reflecting long-term interest rates.
  15. 10Y-2Y Treasury Spread (%): The difference between the yields on 10-year and 2-year U.S. Treasury bonds, often used as an indicator of economic expectations.
  16. WTI Crude ($/bl): The price per barrel of West Texas Intermediate crude oil, a benchmark for U.S. oil prices.
  17. Gold ($/Troy Oz): The price per troy ounce of gold, a standard measure for gold prices.
  18. Bitcoin: A decentralized digital currency without a central bank or single administrator, which can be sent from user to user on the peer-to-peer bitcoin network.

This content was developed by Cambridge and BridgePort from sources believed to be reliable. This content is provided for informational purposes only and should not be construed or acted upon as individualized investment advice. It should not be considered a recommendation or solicitation. Information is subject to change. Any forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. The information in this material is not intended as tax or legal advice.

Investing involves risk. Depending on the different types of investments there may be varying degrees of risk. Socially responsible investing does not guarantee any amount of success. Clients and prospective clients should be prepared to bear investment loss including loss of original principal. Indices mentioned are unmanaged and cannot be invested into directly. Past performance is not a guarantee of future results.

The Dow Jones Industrial Average (DJIA) is a price-weighted index composed of 30 widely traded blue-chip U.S. common stocks. The S&P 500 is a market-cap weighted index composed of the common stocks of 500 leading companies in leading industries of the U.S. economy. The NASDAQ Composite Index is a market-value weighted index of all common stocks listed on the NASDAQ stock exchange.

Securities offered through Cambridge Investment Research, Inc., a broker-dealer, member FINRA/SIPC, and investment advisory services offered through Cambridge Investment Research Advisors, Inc., a Registered Investment Adviser. BridgePort Financial Solutions, LLC is a Registered Investment Adviser with the U.S. Securities & Exchange Commission. All three are wholly-owned subsidiaries of Cambridge Investment Group, Inc. V.CIR.1126-4173
Market Commentary | November 9th, 2026

Weekly Market Commentary

November 9th, 2026

Week in Review

Recent market volatility has understandably raised concerns among investors, particularly following the midterm elections and renewed scrutiny of the significant capital investment supporting AI. While markets are adjusting to a changing political landscape and questions surrounding AI infrastructure spending, we believe it is important to distinguish near-term uncertainty from the underlying economic fundamentals.

As discussed in our quarterly outlook, equity markets have historically delivered positive returns following midterm elections. This pattern is less about which political party wins and more about the reduction in uncertainty once election outcomes become clear. Investors can shift their attention away from political speculation and back toward corporate earnings, economic growth, and monetary policy. The prospect of divided government may also constrain sweeping federal policy changes, although uncertainty surrounding specific policies will likely persist.

One area attracting particular attention is the AI infrastructure buildout. Following the election, proposals for restrictions or temporary moratoriums on new data center development in certain states have raised concerns about the sustainability of AI-related capital expenditures. While these developments introduce potential challenges, we believe underlying demand for computing infrastructure remains strong, supported by continued AI adoption and growing computational requirements across industries. The pace of investment may fluctuate, but the longer-term drivers of demand remain intact.

Importantly, data center development involves years of planning, permitting, grid interconnection, equipment procurement, and financing. Significant investment commitments are already in place, with substantial capacity under construction and additional projects supported by existing agreements. While regulatory changes could delay development, particularly for projects in earlier stages, existing commitments make an immediate reversal of the broader investment cycle less likely. Restrictions in certain regions could also encourage companies to redirect future investment toward markets with more favorable regulatory environments and greater access to power. Such adjustments may affect the timing and location of development without necessarily undermining the long-term demand for AI infrastructure.

Nevertheless, meaningful risks remain. Higher financing costs, regulatory uncertainty, power availability, and questions surrounding returns on AI investment warrant continued monitoring. Strong demand for computing capacity does not guarantee that every project will generate attractive returns, particularly given the substantial capital required. As expectations for AI-related growth remain elevated, markets may be especially sensitive to developments that challenge the anticipated pace of investment or profitability.

Looking ahead, we remain constructive on the long-term demand for AI and the infrastructure required to support its growth. At the same time, we expect market volatility to persist as investors navigate policy uncertainty and reassess expectations for AI-related investment returns. Against this backdrop, we believe maintaining a diversified portfolio and a disciplined, long-term investment approach remain essential to navigating near-term uncertainty while participating in future growth opportunities.

Economic and Capital Markets Dashboard

Broad Market Indices 1-week 1-month 3-month YTD
Stock Market (Total Return)        
S&P 500 -2.67% -5.60% -4.06% 8.78%
Dow Jones 30 -0.94% -0.42% -4.47% 8.06%
NASDAQ -3.37% -10.93% -6.58% 6.25%
Russell 1000 Growth -4.98% -13.49% -9.41% -5.15%
Russell 1000 Value -0.49% 2.29% 0.91% 23.88%
Russell 2000 -2.03% -2.64% -7.95% 12.05%
Wilshire 5000 -2.57% -5.26% -4.25% 8.88%
MSCI EAFE Index -1.46% -2.34% -3.50% 10.75%
MSCI Emerging Market Index -3.83% -12.72% -9.05% 9.87%
VIX 32.03% 70.82% 69.24% 71.51%
FTSE NAREIT All Equity REITs 1.90% 6.43% -1.10% 15.17%
S&P U.S. Aggregate Bond Index 0.33% 2.44% 0.18% 0.22%
Interest Rates 11/6/2026 10/30/2026 10/23/2026 10/16/2026
3-month T-bill Yield (%) 4.10 4.07 4.14 4.17
10-year Treasury Yield (%) 4.86 4.91 5.00 5.08
10Y-2Y Treasury Spread (%) 0.34 0.34 0.31 0.37
30-year Fixed Mortgage Rate (%) 7.28 7.36 7.43 7.51
Commodities        
WTI Crude ($/bl) 90.88 107.56 109.72 108.21
Gold ($/Troy Oz) 4,049.60 3,913.25 4,013.30 4,189.20
Bitcoin 75,866.15 77,172.72 81,035.33 81,477.21
Weekly Indicators 11/6/2026 10/30/2026 10/23/2026 10/16/2026
Employment        
Initial Unemployment Claims (000’s) – 189.00 195.00 195.00
Quarterly Data 9/30/2026 6/30/2026 3/31/2026 12/31/2025
Output        
Real GDP Growth (%q/q, saar) 3.40 2.20 2.50 0.20
Private Consumption (%q/q, saar) 3.80 3.80 0.70 1.90
Monthly Indicators 10/30/2026 9/30/2026 8/31/2026 7/31/2026
Consumption        
Consumer Expenditures (%m/m, sa) – 0.51 0.87 0.23
Retail Sales (%m/m, sa) – 0.72 1.28 -0.55
Personal Savings Rate (%) – 3.80 4.00 4.50
Labor        
Civilian Unemployment Rate (%) 4.10 4.20 4.10 4.10
Nonfarm Employment (Chg, 000’s) 165 60 186 -10
Real Average Hourly Earnings (%y/y) – -0.33 0.01 -0.02
JOLTS Job Openings (000’s) – 7523 7190 7335
Inflation        
Consumer Price Index (CPI) (%m/m, sa) – 0.65 0.40 0.07
Core CPI (%m/m, sa) – 0.33 0.29 0.22
Producer Price Index (PPI) (%m/m, sa) – 1.34 0.47 0.15
Core PPI (%m/m, sa) – 0.27 0.39 0.20
Personal Consumption Expenditures (PCE) (%m/m, sa) – 0.49 0.32 0.06
Core PCE (%m/m, sa) – 0.32 0.26 0.14
Output and Capacity        
Industrial Production (%m/m, sa) – 0.66 0.06 0.23
Mfg New Orders (%m/m, sa) – 1.84 0.33 0.77
Durable New Orders (%m/m, sa) – 1.91 0.14 0.87
Durable Inventories (%m/m, sa) – 0.34 0.53 0.47
Survey Data and Composite Indicators        
Consumer Confidence (CB, 1985=100) 91.70 84.20 88.60 90.20
ISM Manufacturing Report (%) 55.50 54.50 54.60 55.60
ISM Non-Manufacturing Report (%) 54.50 54.90 55.40 54.10
Leading Economic Index (%m/m) – 0.00 -0.10 0.30
Housing and Construction        
Building Permits (Mil. of Units, saar) – 1.40 1.40 1.43
Housing Starts (Mil. of Units, saar) – 1.22 1.29 1.37
New Home Sales (Mil. of Units, saar) – 0.68 0.68 0.65

Week Ahead…

The coming week will provide updates on inflation at both the consumer and producer levels. Markets will focus on whether recent price pressures are showing signs of cooling, and how the data will affect the Federal Reserve’s policy decisions.

Inflation: Consumer and Producer Prices

The October Consumer Price Index (CPI) is scheduled for release next Tuesday. Investors will be looking for signs of cooling, as the Fed is prioritizing bringing inflation back down to its 2% target. September’s 3.7% CPI reading largely reflected a rise in energy prices, and investors will be looking to see how energy and other pricing pressures impact October’s reading. The Fed raised interest rates by 25 basis points in September to 3.75% to 4.00% and held rates steady in October, with markets predicting, as of November 6, a 77% chance that the Fed raises interest rates in December by another 25 basis points.

Along with CPI data, the Producer Price Index (PPI) is scheduled for release next Friday. The data will show how price pressures have been impacting producers, and ultimately how producer prices are impacting retail pricing.

Economic Indicators:

  1. CPI: Consumer Price Index measures the average change in prices paid by consumers for goods and services over time. Source: Bureau of Labor Statistics.
  2. Core CPI: Core Consumer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  3. PPI: Producer Price Index measures the average change in selling prices received by domestic producers for their output. Source: Bureau of Labor Statistics.
  4. Core PPI: Core Producer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  5. PCE: Personal Consumption Expenditures measure the average change in prices paid by consumers for goods and services. Source: Bureau of Economic Analysis.
  6. Core PCE: Core Personal Consumption Expenditures exclude food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Economic Analysis.
  7. Industrial Production: Measures the output of the industrial sector, including manufacturing, mining, and utilities. Source: Federal Reserve.
  8. Mfg New Orders: Measures the value of new orders placed with manufacturers for durable and non-durable goods. Source: Census Bureau.
  9. Durable New Orders: Measures the value of new orders placed with manufacturers of durable goods. Source: Census Bureau.
  10. Durable Inventories: Measures the value of inventories held by manufacturers for durable goods. Source: Census Bureau.
  11. Consumer Confidence (CB, 1985=100): Measures the degree of optimism that consumers feel about the overall state of the economy and their personal financial situation. Source: Conference Board.
  12. ISM Manufacturing Report: Measures the economic health of the manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  13. ISM Non-Manufacturing Report: Measures the economic health of the non-manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  14. Leading Economic Index: Measures overall economic activity and predicts future economic trends. Source: Conference Board.
  15. Building Permits (Mil. of Units, saar): Measures the number of new residential building permits issued. Source: Census Bureau.
  16. Housing Starts (Mil. of Units, saar): Measures the number of new residential construction projects that have begun. Source: Census Bureau.
  17. New Home Sales (Mil. of Units, saar): Measures the number of newly constructed homes sold. Source: Census Bureau.
  18. SA: Seasonally adjusted.
  19. SAAR: Seasonally adjusted annual rate.

Market Indices & Indicators:

  1. S&P 500: A market-capitalization-weighted index of 500 leading publicly traded companies in the U.S., widely regarded as one of the best gauges of large U.S. stocks and the stock market overall.
  2. Dow Jones 30: Also known as the Dow Jones Industrial Average, it tracks the share price performance of 30 large, publicly traded U.S. companies, serving as a barometer of the stock market and economy.
  3. NASDAQ: The world’s first electronic stock exchange, primarily listing technology giants and operating 29 markets globally.
  4. Russell 1000 Growth: Measures the performance of large-cap growth segment of the U.S. equity universe, including companies with higher price-to-book ratios and growth metrics.
  5. Russell 1000 Value: Measures the performance of large-cap value segment of the U.S. equity universe, including companies with lower price-to-book ratios and growth metrics.
  6. Russell 2000: A market index composed of 2,000 small-cap companies, widely used as a benchmark for small-cap mutual funds.
  7. Wilshire 5000: A market-capitalization-weighted index capturing the performance of all American stocks actively traded in the U.S., representing the broadest measure of the U.S. stock market.
  8. MSCI EAFE Index: An equity index capturing large and mid-cap representation across developed markets countries around the world, excluding the U.S. and Canada.
  9. MSCI Emerging Market Index: Captures large and mid-cap representation across emerging markets countries, covering approximately 85% of the free float-adjusted market capitalization in each country.
  10. VIX: The CBOE Volatility Index measures the market’s expectations for volatility over the coming 30 days, often referred to as the “fear gauge.”
  11. FTSE NAREIT All Equity REITs: Measures the performance of all publicly traded equity real estate investment trusts (REITs) listed in the U.S., excluding mortgage REITs.
  12. S&P U.S. Aggregate Bond Index: Represents the performance of the U.S. investment-grade bond market, including government, corporate, mortgage-backed, and asset-backed securities.
  13. 3-Month T-bill Yield (%): The yield on U.S. Treasury bills with a maturity of three months, reflecting short-term interest rates.
  14. 10-Year Treasury Yield (%): The yield on U.S. Treasury bonds with a maturity of ten years, reflecting long-term interest rates.
  15. 10Y-2Y Treasury Spread (%): The difference between the yields on 10-year and 2-year U.S. Treasury bonds, often used as an indicator of economic expectations.
  16. WTI Crude ($/bl): The price per barrel of West Texas Intermediate crude oil, a benchmark for U.S. oil prices.
  17. Gold ($/Troy Oz): The price per troy ounce of gold, a standard measure for gold prices.
  18. Bitcoin: A decentralized digital currency without a central bank or single administrator, which can be sent from user to user on the peer-to-peer bitcoin network.

This content was developed by Cambridge and BridgePort from sources believed to be reliable. This content is provided for informational purposes only and should not be construed or acted upon as individualized investment advice. It should not be considered a recommendation or solicitation. Information is subject to change. Any forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. The information in this material is not intended as tax or legal advice.

Investing involves risk. Depending on the different types of investments there may be varying degrees of risk. Socially responsible investing does not guarantee any amount of success. Clients and prospective clients should be prepared to bear investment loss including loss of original principal. Indices mentioned are unmanaged and cannot be invested into directly. Past performance is not a guarantee of future results.

The Dow Jones Industrial Average (DJIA) is a price-weighted index composed of 30 widely traded blue-chip U.S. common stocks. The S&P 500 is a market-cap weighted index composed of the common stocks of 500 leading companies in leading industries of the U.S. economy. The NASDAQ Composite Index is a market-value weighted index of all common stocks listed on the NASDAQ stock exchange.

Securities offered through Cambridge Investment Research, Inc., a broker-dealer, member FINRA/SIPC, and investment advisory services offered through Cambridge Investment Research Advisors, Inc., a Registered Investment Adviser. BridgePort Financial Solutions, LLC is a Registered Investment Adviser with the U.S. Securities & Exchange Commission. All three are wholly-owned subsidiaries of Cambridge Investment Group, Inc. V.CIR.1126-4099

Market Commentary | November 2nd, 2026

Weekly Market Commentary

November 2nd, 2026

Week in Review

This week’s economic data painted a mixed picture of the U.S. economy, with housing and consumer confidence showing signs of resilience, while spending and manufacturing data were more subdued. Inflation remained elevated, keeping monetary policy at the center of investor attention.

Housing data were generally steady, with some signs of stronger-than-expected demand. Tuesday’s building permits were steady, totaling 1.398 million, roughly in line with expectations of 1.400 million and slightly below the prior month’s 1.403 million reading. New home sales provided a more positive signal, coming in at 676,000 compared with expectations of 651,000. The report showed new home sales declined just 0.6% month-over-month, significantly less than the 4.5% decline anticipated. Following August’s stronger-than-expected report, the latest data further suggests housing demand has remained relatively resilient despite higher borrowing costs.

Consumer data was less consistent. The Conference Board Consumer Confidence Index rose to 91.7 in October, well above expectations of 81.2 and reversing some of the weakness seen in recent months. Meanwhile, September personal spending rose 0.5%, below expectations and notably slower than the prior month’s 0.9% increase. Importantly, the reports cover different periods, making direct comparison difficult. Markets may therefore remain cautious until subsequent spending data show whether October’s improvement in sentiment translates into stronger consumer activity.

Elsewhere, preliminary core durable goods orders increased 0.5%, below the 0.6% consensus estimate but ahead of the prior month’s 0.3% increase, pointing to modest improvement in manufacturing activity.

On the policy front, the Federal Reserve left interest rates unchanged at 3.75% to 4.00% in a divided decision, with two policymakers favoring a 25-basis point increase. The Federal Open Market Committee (FOMC) continued to characterize inflation as elevated while describing economic activity as strong.

On the inflation front, September core and headline Personal Consumption Expenditures (PCE) inflation came in at 0.3% and 0.5% month over month, respectively. Year over year, core PCE remained at 3.1%, while headline PCE stood at 3.6%, leaving both above the Fed’s 2% objective. Despite persistent inflation, Treasury auction yields for 2-, 5-, and 7-year notes came in below their prior month levels. While yields reflect numerous factors, the decline provided an interesting counterpoint to the Fed’s cautious stance and persistent inflation data.

Economic and Capital Markets Dashboard

Broad Market Indices 1-week 1-month 3-month YTD
Stock Market (Total Return)
S&P 500 -0.56% -0.87% 2.19% 11.77%
Dow Jones 30 -0.83% 1.76% -0.47% 9.08%
NASDAQ -1.99% -5.28% 1.40% 9.95%
Russell 1000 Growth -1.70% -6.09% 0.32% -0.17%
Russell 1000 Value 0.48% 4.38% 3.64% 24.50%
Russell 2000 1.30% 0.58% -4.25% 14.37%
Wilshire 5000 -0.44% -0.62% 1.76% 11.75%
MSCI EAFE Index 1.06% -0.44% -0.38% 12.39%
MSCI Emerging Market Index -0.28% -7.44% -0.13% 14.24%
VIX -0.15% 18.85% 13.63% 29.90%
FTSE NAREIT All Equity REITs 1.19% 4.72% -4.48% 13.02%
S&P U.S. Aggregate Bond Index 0.53% 2.25% -0.02% -0.11%
Interest Rates 10/30/2026 10/23/2026 10/16/2026 10/9/2026
3-month T-bill Yield (%) 4.07 4.14 4.17 4.16
10-year Treasury Yield (%) 4.91 5.00 5.08 5.24
10Y-2Y Treasury Spread (%) 0.34 0.31 0.37 0.46
30-year Fixed Mortgage Rate (%) 7.36 7.43 7.51 7.48
Commodities
WTI Crude ($/bl) 104.06 109.72 108.21 98.73
Gold ($/Troy Oz) 3,913.25 4,013.30 4,189.20 4,186.30
Bitcoin 77,172.72 81,035.33 81,477.21 82,538.43


Weekly Indicators 10/30/2026 10/23/2026 10/16/2026 10/9/2026
Employment
Initial Unemployment Claims (000’s) – 194.00 195.00 200.00


Quarterly Data 9/30/2026 6/30/2026 3/31/2026 12/31/2025
Output
Real GDP Growth (%q/q, saar) 3.40 2.20 2.50 0.20
Private Consumption (%q/q, saar) 3.80 3.80 0.70 1.90


Monthly Indicators 10/30/2026 9/30/2026 8/31/2026 7/31/2026
Consumption
Consumer Expenditures (%m/m, sa) – 0.51 0.87 0.23
Retail Sales (%m/m, sa) – 0.72 1.28 -0.55
Personal Savings Rate (%) – 3.80 4.00 4.50
Labor
Civilian Unemployment Rate (%) – 4.20 4.10 4.10
Nonfarm Employment (Chg, 000’s) – 29 133 -10
Real Average Hourly Earnings (%y/y) – -0.42 -0.05 -0.02
JOLTS Job Openings (000’s) – – 7079 7335
Inflation
Consumer Price Index (CPI) (%m/m, sa) – 0.65 0.40 0.07
Core CPI (%m/m, sa) – 0.33 0.29 0.22
Producer Price Index (PPI) (%m/m, sa) – 1.34 0.47 0.15
Core PPI (%m/m, sa) – 0.27 0.39 0.20
Personal Consumption Expenditures (PCE) (%m/m, sa) – 0.49 0.32 0.06
Core PCE (%m/m, sa) – 0.32 0.26 0.14
Output and Capacity
Industrial Production (%m/m, sa) – 0.66 0.06 0.23
Mfg New Orders (%m/m, sa) – – 0.10 0.77
Durable New Orders (%m/m, sa) – 1.84 0.12 0.87
Durable Inventories (%m/m, sa) – 0.31 0.51 0.47
Survey Data and Composite Indicators
Consumer Confidence (CB, 1985=100) 91.70 84.20 88.60 90.20
ISM Manufacturing Report (%) – 54.50 54.60 55.60
ISM Non-Manufacturing Report (%) – 54.90 55.40 54.10
Leading Economic Index (%m/m) – 0.00 -0.10 0.30
Housing and Construction
Building Permits (Mil. of Units, saar) – 1.40 1.40 1.43
Housing Starts (Mil. of Units, saar) – 1.22 1.29 1.37
New Home Sales (Mil. of Units, saar) – 0.68 0.68 0.65

Week Ahead…

Next week will be a busy one for economic data, with several reports providing updates on business activity, inflation pressures, and the labor market.

Markets will receive October manufacturing data on Monday with the release of the S&P Global Manufacturing Purchasing Managers’ Index (PMI) and Institute for Supply Management (ISM) Manufacturing Index, followed by their services counterparts on Wednesday. Beyond the headline readings, investors will likely pay particular attention to the prices and employment components for signs of changing inflationary pressures or labor market weakness. The services reports may be especially important given the sector’s larger contribution to overall economic activity.

Employment will remain a major focus throughout the week. September’s Job Openings and Labor Turnover Survey (JOLTS) on Tuesday will provide additional insight into labor supply and demand, while Friday’s employment report will include nonfarm payrolls, the unemployment rate, U6 unemployment, and labor force participation. A meaningful surprise in either direction could challenge the Federal Reserve’s recent characterization of economic activity as strong and influence expectations surrounding its next policy decision.

Inflation will also remain in focus. Preliminary University of Michigan inflation expectations are due Friday, providing another view of inflation pressures alongside the ISM price indexes. Third-quarter nonfarm productivity and unit labor costs will offer additional context. Productivity growth can allow wages to rise without creating the same degree of inflationary pressure, while unit labor costs provide insight into how labor expenses are evolving relative to output.

Economic Indicators:

  1. CPI: Consumer Price Index measures the average change in prices paid by consumers for goods and services over time. Source: Bureau of Labor Statistics.
  2. Core CPI: Core Consumer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  3. PPI: Producer Price Index measures the average change in selling prices received by domestic producers for their output. Source: Bureau of Labor Statistics.
  4. Core PPI: Core Producer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  5. PCE: Personal Consumption Expenditures measure the average change in prices paid by consumers for goods and services. Source: Bureau of Economic Analysis.
  6. Core PCE: Core Personal Consumption Expenditures exclude food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Economic Analysis.
  7. Industrial Production: Measures the output of the industrial sector, including manufacturing, mining, and utilities. Source: Federal Reserve.
  8. Mfg New Orders: Measures the value of new orders placed with manufacturers for durable and non-durable goods. Source: Census Bureau.
  9. Durable New Orders: Measures the value of new orders placed with manufacturers of durable goods. Source: Census Bureau.
  10. Durable Inventories: Measures the value of inventories held by manufacturers for durable goods. Source: Census Bureau.
  11. Consumer Confidence (CB, 1985=100): Measures the degree of optimism that consumers feel about the overall state of the economy and their personal financial situation. Source: Conference Board.
  12. ISM Manufacturing Report: Measures the economic health of the manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  13. ISM Non-Manufacturing Report: Measures the economic health of the non-manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  14. Leading Economic Index: Measures overall economic activity and predicts future economic trends. Source: Conference Board.
  15. Building Permits (Mil. of Units, saar): Measures the number of new residential building permits issued. Source: Census Bureau.
  16. Housing Starts (Mil. of Units, saar): Measures the number of new residential construction projects that have begun. Source: Census Bureau.
  17. New Home Sales (Mil. of Units, saar): Measures the number of newly constructed homes sold. Source: Census Bureau.
  18. SA: Seasonally adjusted.
  19. SAAR: Seasonally adjusted annual rate.

Market Indices & Indicators:

  1. S&P 500: A market-capitalization-weighted index of 500 leading publicly traded companies in the U.S., widely regarded as one of the best gauges of large U.S. stocks and the stock market overall.
  2. Dow Jones 30: Also known as the Dow Jones Industrial Average, it tracks the share price performance of 30 large, publicly traded U.S. companies, serving as a barometer of the stock market and economy.
  3. NASDAQ: The world’s first electronic stock exchange, primarily listing technology giants and operating 29 markets globally.
  4. Russell 1000 Growth: Measures the performance of large-cap growth segment of the U.S. equity universe, including companies with higher price-to-book ratios and growth metrics.
  5. Russell 1000 Value: Measures the performance of large-cap value segment of the U.S. equity universe, including companies with lower price-to-book ratios and growth metrics.
  6. Russell 2000: A market index composed of 2,000 small-cap companies, widely used as a benchmark for small-cap mutual funds.
  7. Wilshire 5000: A market-capitalization-weighted index capturing the performance of all American stocks actively traded in the U.S., representing the broadest measure of the U.S. stock market.
  8. MSCI EAFE Index: An equity index capturing large and mid-cap representation across developed markets countries around the world, excluding the U.S. and Canada.
  9. MSCI Emerging Market Index: Captures large and mid-cap representation across emerging markets countries, covering approximately 85% of the free float-adjusted market capitalization in each country.
  10. VIX: The CBOE Volatility Index measures the market’s expectations for volatility over the coming 30 days, often referred to as the “fear gauge.”
  11. FTSE NAREIT All Equity REITs: Measures the performance of all publicly traded equity real estate investment trusts (REITs) listed in the U.S., excluding mortgage REITs.
  12. S&P U.S. Aggregate Bond Index: Represents the performance of the U.S. investment-grade bond market, including government, corporate, mortgage-backed, and asset-backed securities.
  13. 3-Month T-bill Yield (%): The yield on U.S. Treasury bills with a maturity of three months, reflecting short-term interest rates.
  14. 10-Year Treasury Yield (%): The yield on U.S. Treasury bonds with a maturity of ten years, reflecting long-term interest rates.
  15. 10Y-2Y Treasury Spread (%): The difference between the yields on 10-year and 2-year U.S. Treasury bonds, often used as an indicator of economic expectations.
  16. WTI Crude ($/bl): The price per barrel of West Texas Intermediate crude oil, a benchmark for U.S. oil prices.
  17. Gold ($/Troy Oz): The price per troy ounce of gold, a standard measure for gold prices.
  18. Bitcoin: A decentralized digital currency without a central bank or single administrator, which can be sent from user to user on the peer-to-peer bitcoin network.

This content was developed by Cambridge and BridgePort from sources believed to be reliable. This content is provided for informational purposes only and should not be construed or acted upon as individualized investment advice. It should not be considered a recommendation or solicitation. Information is subject to change. Any forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. The information in this material is not intended as tax or legal advice.

Investing involves risk. Depending on the different types of investments there may be varying degrees of risk. Socially responsible investing does not guarantee any amount of success. Clients and prospective clients should be prepared to bear investment loss including loss of original principal. Indices mentioned are unmanaged and cannot be invested into directly. Past performance is not a guarantee of future results.

The Dow Jones Industrial Average (DJIA) is a price-weighted index composed of 30 widely traded blue-chip U.S. common stocks. The S&P 500 is a market-cap weighted index composed of the common stocks of 500 leading companies in leading industries of the U.S. economy. The NASDAQ Composite Index is a market-value weighted index of all common stocks listed on the NASDAQ stock exchange.

Securities offered through Cambridge Investment Research, Inc., a broker-dealer, member FINRA/SIPC, and investment advisory services offered through Cambridge Investment Research Advisors, Inc., a Registered Investment Adviser. BridgePort Financial Solutions, LLC is a Registered Investment Adviser with the U.S. Securities & Exchange Commission. All three are wholly-owned subsidiaries of Cambridge Investment Group, Inc. V.CIR.1126-4012

Market Commentary | October 26th, 2026

Weekly Market Commentary

October 26th, 2026

Week in Review

Last week’s economic data generally pointed to a resilient economy entering the fourth quarter. Business activity and labor market conditions remained supportive of growth, although housing activity remained weak and persistent price pressures continued to be a concern.

September housing starts fell 5.2% to an annualized pace of 1.221 million, below expectations of 1.300 million. Building permits were little changed at 1.400 million, as elevated mortgage rates, construction costs, and affordability constraints continued to weigh on housing activity.

Labor market conditions remained stable, with initial jobless claims declining to 194,000 from 199,000 the previous week. Regional manufacturing activity showed some moderation, with the Kansas City Fed Manufacturing Composite Index declining to 11 in October from 14 in September as growth in both durable and nondurable manufacturing slowed. However, expectations for future activity improved to 22 from 19, suggesting manufacturers remained relatively optimistic about the months ahead.

Business activity remained strong entering the fourth quarter, despite some moderation in the services sector. October Manufacturing Purchasing Managers’ Index (PMI) increased to 56.0 from 55.9, while Services PMI declined to 57.9 from 58.8, bringing Composite PMI down to 57.6 from 58.4. The overall reading remained firmly in expansion territory, with new orders and hiring continuing to improve. However, selling prices rose at their fastest pace since August 2022 as businesses passed higher input costs on to customers, adding to concerns that inflationary pressures remain persistent.

The October University of Michigan Consumer Sentiment Index remained subdued at 48.0, little changed from September. The Current Conditions reading fell to 46.7 from 50.9 but came in above expectations of 44.7, suggesting conditions weakened but not as much as anticipated. Year-ahead inflation expectations also increased to 4.7% from 4.6%, reinforcing concerns that higher prices continue to weigh on household confidence.

Economic and Capital Markets Dashboard

Broad Market Indices 1-week 1-month 3-month YTD
Stock Market (Total Return)
S&P 500 -0.46% -1.00% 3.19% 12.40%
Dow Jones 30 0.42% 1.41% 1.34% 9.99%
NASDAQ -0.71% -3.63% 3.40% 12.19%
Russell 1000 Growth -1.52% -4.57% 0.97% 1.55%
Russell 1000 Value 0.67% 2.42% 5.01% 23.90%
Russell 2000 2.01% -2.12% -5.28% 12.90%
Wilshire 5000 -0.27% -1.02% 2.64% 12.24%
MSCI EAFE Index -1.62% -1.61% -0.96% 11.21%
MSCI Emerging Market Index -2.50% -9.21% -6.77% 14.55%
VIX -2.70% 28.13% 4.01% 30.10%
FTSE NAREIT All Equity REITs 1.21% 1.62% -5.34% 11.70%
S&P U.S. Aggregate Bond Index 0.49% 0.81% -0.31% -0.64%
Interest Rates 10/23/2026 10/16/2026 10/9/2026 10/2/2026
3-month T-bill Yield (%) 4.14 4.17 4.16 4.10
10-year Treasury Yield (%) 5.00 5.08 5.24 5.28
10Y-2Y Treasury Spread (%) 0.31 0.37 0.46 0.44
30-year Fixed Mortgage Rate (%) 7.43 7.51 7.48 7.30
Commodities
WTI Crude ($/bl) 103.17 108.21 98.73 97.89
Gold ($/Troy Oz) 4,013.30 4,189.20 4,186.30 4,190.05
Bitcoin 81,035.33 81,477.21 82,538.43 84,482.24
Weekly Indicators 10/23/2026 10/16/2026 10/9/2026 10/2/2026
Employment
Initial Unemployment Claims (000’s) – 194.00 200.00 198.00
Quarterly Data 9/30/2026 6/30/2026 3/31/2026 12/31/2025
Output
Real GDP Growth (%q/q, saar) – 2.20 2.50 0.20
Private Consumption (%q/q, saar) – 3.80 0.70 1.90
Monthly Indicators 9/30/2026 8/31/2026 7/31/2026 6/30/2026
Consumption
Consumer Expenditures (%m/m, sa) – 0.86 0.10 0.31
Retail Sales (%m/m, sa) 0.72 1.28 -0.55 0.14
Personal Savings Rate (%) – 4.10 4.60 4.40
Labor
Civilian Unemployment Rate (%) 4.20 4.10 4.10 4.20
Nonfarm Employment (Chg, 000’s) 29 133 -10 31
Real Average Hourly Earnings (%y/y) -0.42 -0.05 -0.02 -0.05
JOLTS Job Openings (000’s) – 7079 7335 7182
Inflation
Consumer Price Index (CPI) (%m/m, sa) 0.65 0.40 0.07 -0.42
Core CPI (%m/m, sa) 0.33 0.29 0.22 -0.02
Producer Price Index (PPI) (%m/m, sa) 1.34 0.47 0.15 -0.12
Core PPI (%m/m, sa) 0.27 0.39 0.20 0.22
Personal Consumption Expenditures (PCE) (%m/m, sa) – 0.31 0.05 -0.10
Core PCE (%m/m, sa) – 0.25 0.13 0.13
Output and Capacity
Industrial Production (%m/m, sa) 0.66 0.06 0.23 0.23
Mfg New Orders (%m/m, sa) – 0.10 0.77 -0.16
Durable New Orders (%m/m, sa) – -0.07 0.87 0.58
Durable Inventories (%m/m, sa) – 0.54 0.47 0.38
Survey Data and Composite Indicators
Consumer Confidence (CB, 1985=100) 81.90 88.60 90.20 92.20
ISM Manufacturing Report (%) 54.50 54.60 55.60 53.30
ISM Non-Manufacturing Report (%) 54.90 55.40 54.10 54.00
Leading Economic Index (%m/m) 0.00 -0.10 0.30 0.00
Housing and Construction
Building Permits (Mil. of Units, saar) 1.40 1.40 1.43 1.37
Housing Starts (Mil. of Units, saar) 1.22 1.29 1.37 1.44
New Home Sales (Mil. of Units, saar) – 0.68 0.64 0.67

Week Ahead…

The upcoming week features a busy economic calendar as investors assess the outlook for growth, inflation, and monetary policy heading into the final months of the year. Recent data have continued to point to resilient economic activity, although persistent price pressures remain a concern and could complicate the path forward for monetary policy.

Tuesday’s September durable goods orders will provide an updated look at business investment and demand for manufactured goods. Consumer confidence and new home sales will also offer further perspective on household sentiment and the housing market, where elevated borrowing costs and affordability constraints remain headwinds.

Wednesday’s Federal Open Market Committee meeting will be the week’s primary focus. Investors will closely monitor the Fed’s policy decision and accompanying statement for guidance on how officials are balancing persistent inflation against the broader growth and labor market outlook.

Thursday will bring several important updates on growth and inflation, led by the advanced estimate of third quarter gross domestic product (GDP) and September Personal Consumption Expenditures (PCE) inflation. GDP will provide an updated assessment of economic growth, while core PCE, the Fed’s preferred measure of underlying inflation, will be closely watched for signs that price pressures remain persistent. Personal spending and weekly initial jobless claims will provide additional perspective on consumer activity and labor market conditions.

Friday’s Chicago PMI will provide an updated look at regional manufacturing activity, with attention focused on whether recent strength can continue. The third-quarter Employment Cost Index will also provide further insight into wage pressures and their potential impact on inflation. Taken together, the week’s data should provide a clearer picture of economic momentum and the monetary policy outlook through the end of the year.

Economic Indicators:

  1. CPI: Consumer Price Index measures the average change in prices paid by consumers for goods and services over time. Source: Bureau of Labor Statistics.
  2. Core CPI: Core Consumer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  3. PPI: Producer Price Index measures the average change in selling prices received by domestic producers for their output. Source: Bureau of Labor Statistics.
  4. Core PPI: Core Producer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  5. PCE: Personal Consumption Expenditures measure the average change in prices paid by consumers for goods and services. Source: Bureau of Economic Analysis.
  6. Core PCE: Core Personal Consumption Expenditures exclude food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Economic Analysis.
  7. Industrial Production: Measures the output of the industrial sector, including manufacturing, mining, and utilities. Source: Federal Reserve.
  8. Mfg New Orders: Measures the value of new orders placed with manufacturers for durable and non-durable goods. Source: Census Bureau.
  9. Durable New Orders: Measures the value of new orders placed with manufacturers of durable goods. Source: Census Bureau.
  10. Durable Inventories: Measures the value of inventories held by manufacturers for durable goods. Source: Census Bureau.
  11. Consumer Confidence (CB, 1985=100): Measures the degree of optimism that consumers feel about the overall state of the economy and their personal financial situation. Source: Conference Board.
  12. ISM Manufacturing Report: Measures the economic health of the manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  13. ISM Non-Manufacturing Report: Measures the economic health of the non-manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  14. Leading Economic Index: Measures overall economic activity and predicts future economic trends. Source: Conference Board.
  15. Building Permits (Mil. of Units, saar): Measures the number of new residential building permits issued. Source: Census Bureau.
  16. Housing Starts (Mil. of Units, saar): Measures the number of new residential construction projects that have begun. Source: Census Bureau.
  17. New Home Sales (Mil. of Units, saar): Measures the number of newly constructed homes sold. Source: Census Bureau.
  18. SA: Seasonally adjusted.
  19. SAAR: Seasonally adjusted annual rate.

Market Indices & Indicators:

  1. S&P 500: A market-capitalization-weighted index of 500 leading publicly traded companies in the U.S., widely regarded as one of the best gauges of large U.S. stocks and the stock market overall.
  2. Dow Jones 30: Also known as the Dow Jones Industrial Average, it tracks the share price performance of 30 large, publicly traded U.S. companies, serving as a barometer of the stock market and economy.
  3. NASDAQ: The world’s first electronic stock exchange, primarily listing technology giants and operating 29 markets globally.
  4. Russell 1000 Growth: Measures the performance of large-cap growth segment of the U.S. equity universe, including companies with higher price-to-book ratios and growth metrics.
  5. Russell 1000 Value: Measures the performance of large-cap value segment of the U.S. equity universe, including companies with lower price-to-book ratios and growth metrics.
  6. Russell 2000: A market index composed of 2,000 small-cap companies, widely used as a benchmark for small-cap mutual funds.
  7. Wilshire 5000: A market-capitalization-weighted index capturing the performance of all American stocks actively traded in the U.S., representing the broadest measure of the U.S. stock market.
  8. MSCI EAFE Index: An equity index capturing large and mid-cap representation across developed markets countries around the world, excluding the U.S. and Canada.
  9. MSCI Emerging Market Index: Captures large and mid-cap representation across emerging markets countries, covering approximately 85% of the free float-adjusted market capitalization in each country.
  10. VIX: The CBOE Volatility Index measures the market’s expectations for volatility over the coming 30 days, often referred to as the “fear gauge.”
  11. FTSE NAREIT All Equity REITs: Measures the performance of all publicly traded equity real estate investment trusts (REITs) listed in the U.S., excluding mortgage REITs.
  12. S&P U.S. Aggregate Bond Index: Represents the performance of the U.S. investment-grade bond market, including government, corporate, mortgage-backed, and asset-backed securities.
  13. 3-Month T-bill Yield (%): The yield on U.S. Treasury bills with a maturity of three months, reflecting short-term interest rates.
  14. 10-Year Treasury Yield (%): The yield on U.S. Treasury bonds with a maturity of ten years, reflecting long-term interest rates.
  15. 10Y-2Y Treasury Spread (%): The difference between the yields on 10-year and 2-year U.S. Treasury bonds, often used as an indicator of economic expectations.
  16. WTI Crude ($/bl): The price per barrel of West Texas Intermediate crude oil, a benchmark for U.S. oil prices.
  17. Gold ($/Troy Oz): The price per troy ounce of gold, a standard measure for gold prices.
  18. Bitcoin: A decentralized digital currency without a central bank or single administrator, which can be sent from user to user on the peer-to-peer bitcoin network.

This content was developed by Cambridge and BridgePort from sources believed to be reliable. This content is provided for informational purposes only and should not be construed or acted upon as individualized investment advice. It should not be considered a recommendation or solicitation. Information is subject to change. Any forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. The information in this material is not intended as tax or legal advice.

Investing involves risk. Depending on the different types of investments there may be varying degrees of risk. Socially responsible investing does not guarantee any amount of success. Clients and prospective clients should be prepared to bear investment loss including loss of original principal. Indices mentioned are unmanaged and cannot be invested into directly. Past performance is not a guarantee of future results.

The Dow Jones Industrial Average (DJIA) is a price-weighted index composed of 30 widely traded blue-chip U.S. common stocks. The S&P 500 is a market-cap weighted index composed of the common stocks of 500 leading companies in leading industries of the U.S. economy. The NASDAQ Composite Index is a market-value weighted index of all common stocks listed on the NASDAQ stock exchange.

Securities offered through Cambridge Investment Research, Inc., a broker-dealer, member FINRA/SIPC, and investment advisory services offered through Cambridge Investment Research Advisors, Inc., a Registered Investment Adviser. BridgePort Financial Solutions, LLC is a Registered Investment Adviser with the U.S. Securities & Exchange Commission. All three are wholly-owned subsidiaries of Cambridge Investment Group, Inc. V.CIR.1026-3881

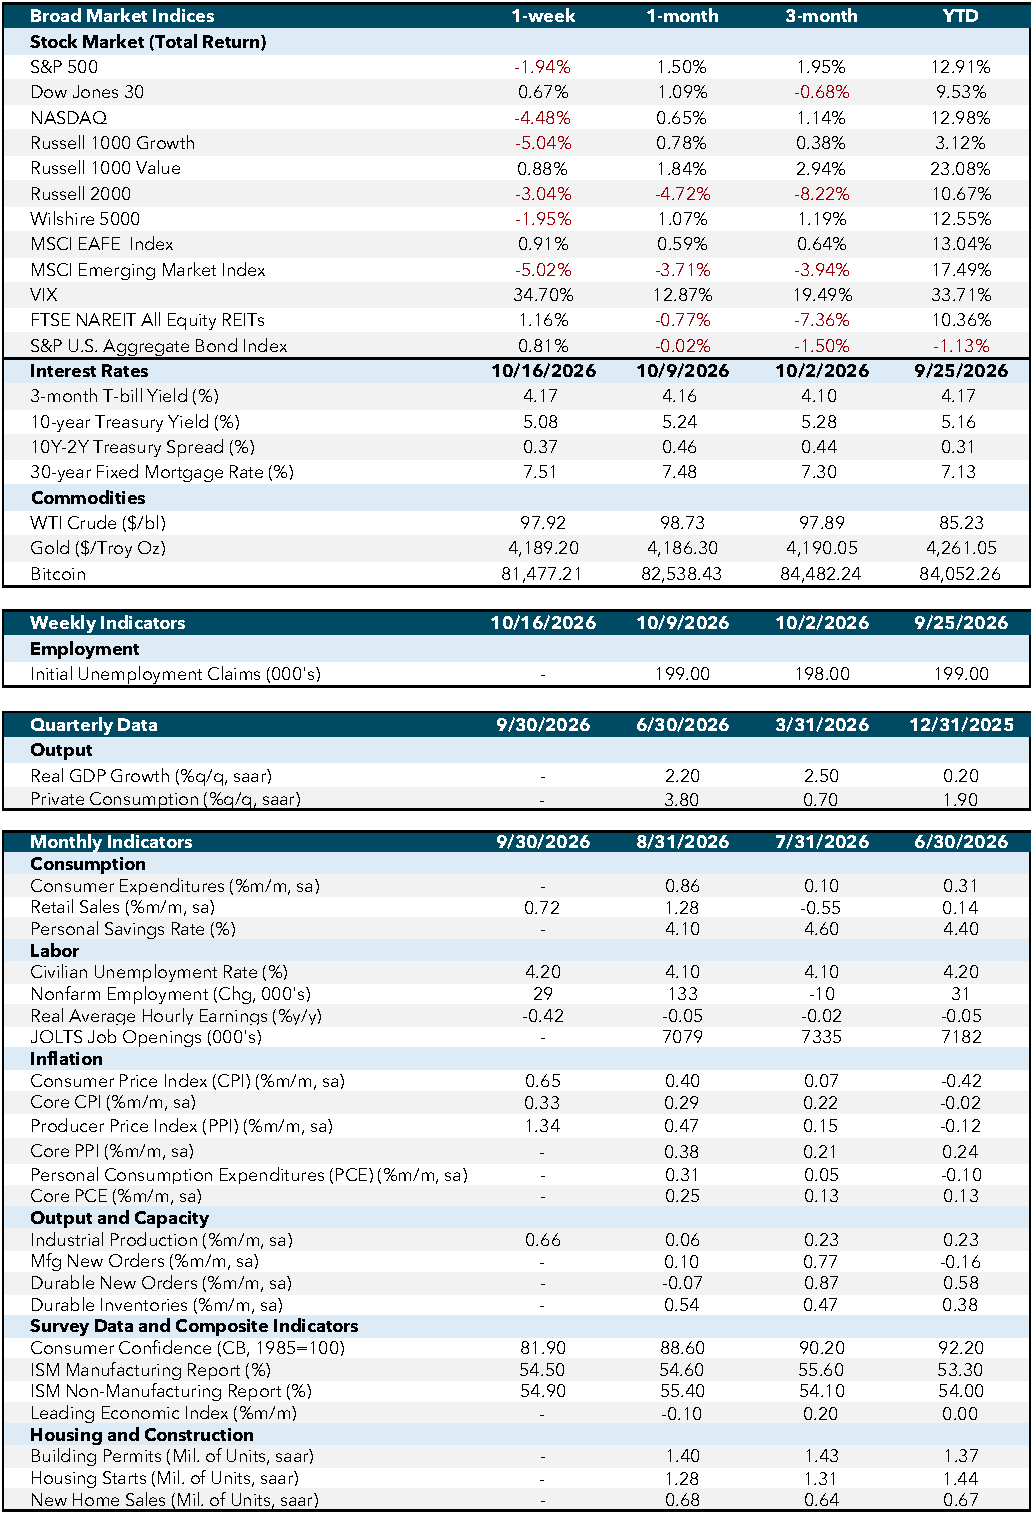
Market Commentary | October 19th, 2026

Weekly Market Commentary

October 19th, 2026

Week in Review

U.S. inflation accelerated in September, reflecting higher energy prices and persistent underlying price pressures. The Consumer Price Index (CPI) increased 0.6% month-over-month, bringing the annual inflation rate to 3.7%, up from 3.4% in August. Gasoline prices surged 9.1%, accounting for more than half of the monthly increase, while shelter costs rose 0.4%. Core CPI, which excludes food and energy, increased 0.3% for the month and 2.6% year-over-year. Producer inflation also came in hotter than expected, with the Producer Price Index (PPI) rising 1.3% month-over-month, significantly above the 0.6% consensus estimate and marking its largest monthly increase since March 2022. Core PPI increased 0.7%, suggesting that price pressures are extending beyond energy.

Consumer spending continued to demonstrate resilience, although underlying demand showed signs of moderation. September retail sales rose 0.8% month-over-month, exceeding expectations of 0.3%, while sales excluding autos increased 0.9%. However, higher gasoline prices contributed to the headline figures, and the retail sales control group increased just 0.1%, suggesting softer underlying consumption. Meanwhile, September existing home sales increased 1.5% to an annualized pace of 3.99 million units, despite continued affordability challenges and elevated mortgage rates. Labor market conditions remained relatively stable, with initial jobless claims totaling 199,000, broadly in line with expectations.

The Federal Reserve’s latest Beige Book, released Wednesday, indicated that economic activity expanded slightly to moderately across most districts, although consumer spending remained largely unchanged. Manufacturing activity improved in several regions, while employment growth remained modest as businesses continued to exercise caution in hiring. The report also highlighted intensifying cost pressures from energy, tariffs, and transportation, with some businesses passing higher expenses on to consumers.

Overall, the week’s economic data reinforced concerns that inflation remains elevated despite relatively stable economic activity. With headline inflation moving further above the Fed’s 2% target, policymakers face an increasingly difficult balance between containing price pressures and preserving economic growth ahead of the October 27-28 Federal Open Market Committee (FOMC) meeting.

Economic and Capital Markets Dashboard

Week Ahead…

The upcoming week features a lighter economic calendar, with attention focused on housing activity, labor market conditions, and preliminary business activity indicators. September housing starts and building permits will provide an updated assessment of residential construction amid elevated mortgage rates, rising material costs, and persistent affordability constraints. Housing starts are expected to show a modest rebound following recent weakness, although continued pressure on builders and prospective buyers could limit the recovery. Additional housing indicators will help assess whether demand is stabilizing heading into the final quarter of the year.

Labor market conditions will remain in focus, with Thursday’s weekly initial jobless claims providing insight into whether employers are beginning to reduce staffing amid rising operating costs. The Conference Board’s Leading Economic Index and the Kansas City Fed Manufacturing Survey will offer further perspective on economic momentum, particularly whether manufacturing improvements are broadening across regions.

Friday’s preliminary October S&P Global manufacturing and services Purchasing Managers’ Index (PMI) readings will be among the week’s most closely watched releases. Particular attention will be paid to new orders, employment, and input prices to assess whether inflationary pressures are becoming more persistent. The University of Michigan’s final October consumer sentiment report will also provide updated readings on household confidence and inflation expectations. With Federal Reserve officials entering their blackout period ahead of the October policy meeting, these releases will be important in assessing whether inflationary pressures are moderating or warrant additional monetary tightening.

Economic Indicators:

  1. CPI: Consumer Price Index measures the average change in prices paid by consumers for goods and services over time. Source: Bureau of Labor Statistics.
  2. Core CPI: Core Consumer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  3. PPI: Producer Price Index measures the average change in selling prices received by domestic producers for their output. Source: Bureau of Labor Statistics.
  4. Core PPI: Core Producer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  5. PCE: Personal Consumption Expenditures measure the average change in prices paid by consumers for goods and services. Source: Bureau of Economic Analysis.
  6. Core PCE: Core Personal Consumption Expenditures exclude food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Economic Analysis.
  7. Industrial Production: Measures the output of the industrial sector, including manufacturing, mining, and utilities. Source: Federal Reserve.
  8. Mfg New Orders: Measures the value of new orders placed with manufacturers for durable and non-durable goods. Source: Census Bureau.
  9. Durable New Orders: Measures the value of new orders placed with manufacturers of durable goods. Source: Census Bureau.
  10. Durable Inventories: Measures the value of inventories held by manufacturers for durable goods. Source: Census Bureau.
  11. Consumer Confidence (CB, 1985=100): Measures the degree of optimism that consumers feel about the overall state of the economy and their personal financial situation. Source: Conference Board.
  12. ISM Manufacturing Report: Measures the economic health of the manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  13. ISM Non-Manufacturing Report: Measures the economic health of the non-manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  14. Leading Economic Index: Measures overall economic activity and predicts future economic trends. Source: Conference Board.
  15. Building Permits (Mil. of Units, saar): Measures the number of new residential building permits issued. Source: Census Bureau.
  16. Housing Starts (Mil. of Units, saar): Measures the number of new residential construction projects that have begun. Source: Census Bureau.
  17. New Home Sales (Mil. of Units, saar): Measures the number of newly constructed homes sold. Source: Census Bureau.
  18. SA: Seasonally adjusted.
  19. SAAR: Seasonally adjusted annual rate.

Market Indices & Indicators:

  1. S&P 500: A market-capitalization-weighted index of 500 leading publicly traded companies in the U.S., widely regarded as one of the best gauges of large U.S. stocks and the stock market overall.
  2. Dow Jones 30: Also known as the Dow Jones Industrial Average, it tracks the share price performance of 30 large, publicly traded U.S. companies, serving as a barometer of the stock market and economy.
  3. NASDAQ: The world’s first electronic stock exchange, primarily listing technology giants and operating 29 markets globally.
  4. Russell 1000 Growth: Measures the performance of large-cap growth segment of the U.S. equity universe, including companies with higher price-to-book ratios and growth metrics.
  5. Russell 1000 Value: Measures the performance of large-cap value segment of the U.S. equity universe, including companies with lower price-to-book ratios and growth metrics.
  6. Russell 2000: A market index composed of 2,000 small-cap companies, widely used as a benchmark for small-cap mutual funds.
  7. Wilshire 5000: A market-capitalization-weighted index capturing the performance of all American stocks actively traded in the U.S., representing the broadest measure of the U.S. stock market.
  8. MSCI EAFE Index: An equity index capturing large and mid-cap representation across developed markets countries around the world, excluding the U.S. and Canada.
  9. MSCI Emerging Market Index: Captures large and mid-cap representation across emerging markets countries, covering approximately 85% of the free float-adjusted market capitalization in each country.
  10. VIX: The CBOE Volatility Index measures the market’s expectations for volatility over the coming 30 days, often referred to as the “fear gauge.”
  11. FTSE NAREIT All Equity REITs: Measures the performance of all publicly traded equity real estate investment trusts (REITs) listed in the U.S., excluding mortgage REITs.
  12. S&P U.S. Aggregate Bond Index: Represents the performance of the U.S. investment-grade bond market, including government, corporate, mortgage-backed, and asset-backed securities.
  13. 3-Month T-bill Yield (%): The yield on U.S. Treasury bills with a maturity of three months, reflecting short-term interest rates.
  14. 10-Year Treasury Yield (%): The yield on U.S. Treasury bonds with a maturity of ten years, reflecting long-term interest rates.
  15. 10Y-2Y Treasury Spread (%): The difference between the yields on 10-year and 2-year U.S. Treasury bonds, often used as an indicator of economic expectations.
  16. WTI Crude ($/bl): The price per barrel of West Texas Intermediate crude oil, a benchmark for U.S. oil prices.
  17. Gold ($/Troy Oz): The price per troy ounce of gold, a standard measure for gold prices.
  18. Bitcoin: A decentralized digital currency without a central bank or single administrator, which can be sent from user to user on the peer-to-peer bitcoin network.

This content was developed by Cambridge and BridgePort from sources believed to be reliable. This content is provided for informational purposes only and should not be construed or acted upon as individualized investment advice. It should not be considered a recommendation or solicitation. Information is subject to change. Any forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. The information in this material is not intended as tax or legal advice.

Investing involves risk. Depending on the different types of investments there may be varying degrees of risk. Socially responsible investing does not guarantee any amount of success. Clients and prospective clients should be prepared to bear investment loss including loss of original principal. Indices mentioned are unmanaged and cannot be invested into directly. Past performance is not a guarantee of future results.

The Dow Jones Industrial Average (DJIA) is a price-weighted index composed of 30 widely traded blue-chip U.S. common stocks. The S&P 500 is a market-cap weighted index composed of the common stocks of 500 leading companies in leading industries of the U.S. economy. The NASDAQ Composite Index is a market-value weighted index of all common stocks listed on the NASDAQ stock exchange.

Securities offered through Cambridge Investment Research, Inc., a broker-dealer, member FINRA/SIPC, and investment advisory services offered through Cambridge Investment Research Advisors, Inc., a Registered Investment Adviser. BridgePort Financial Solutions, LLC is a Registered Investment Adviser with the U.S. Securities & Exchange Commission. All three are wholly-owned subsidiaries of Cambridge Investment Group, Inc. V.CIR.1026-3881

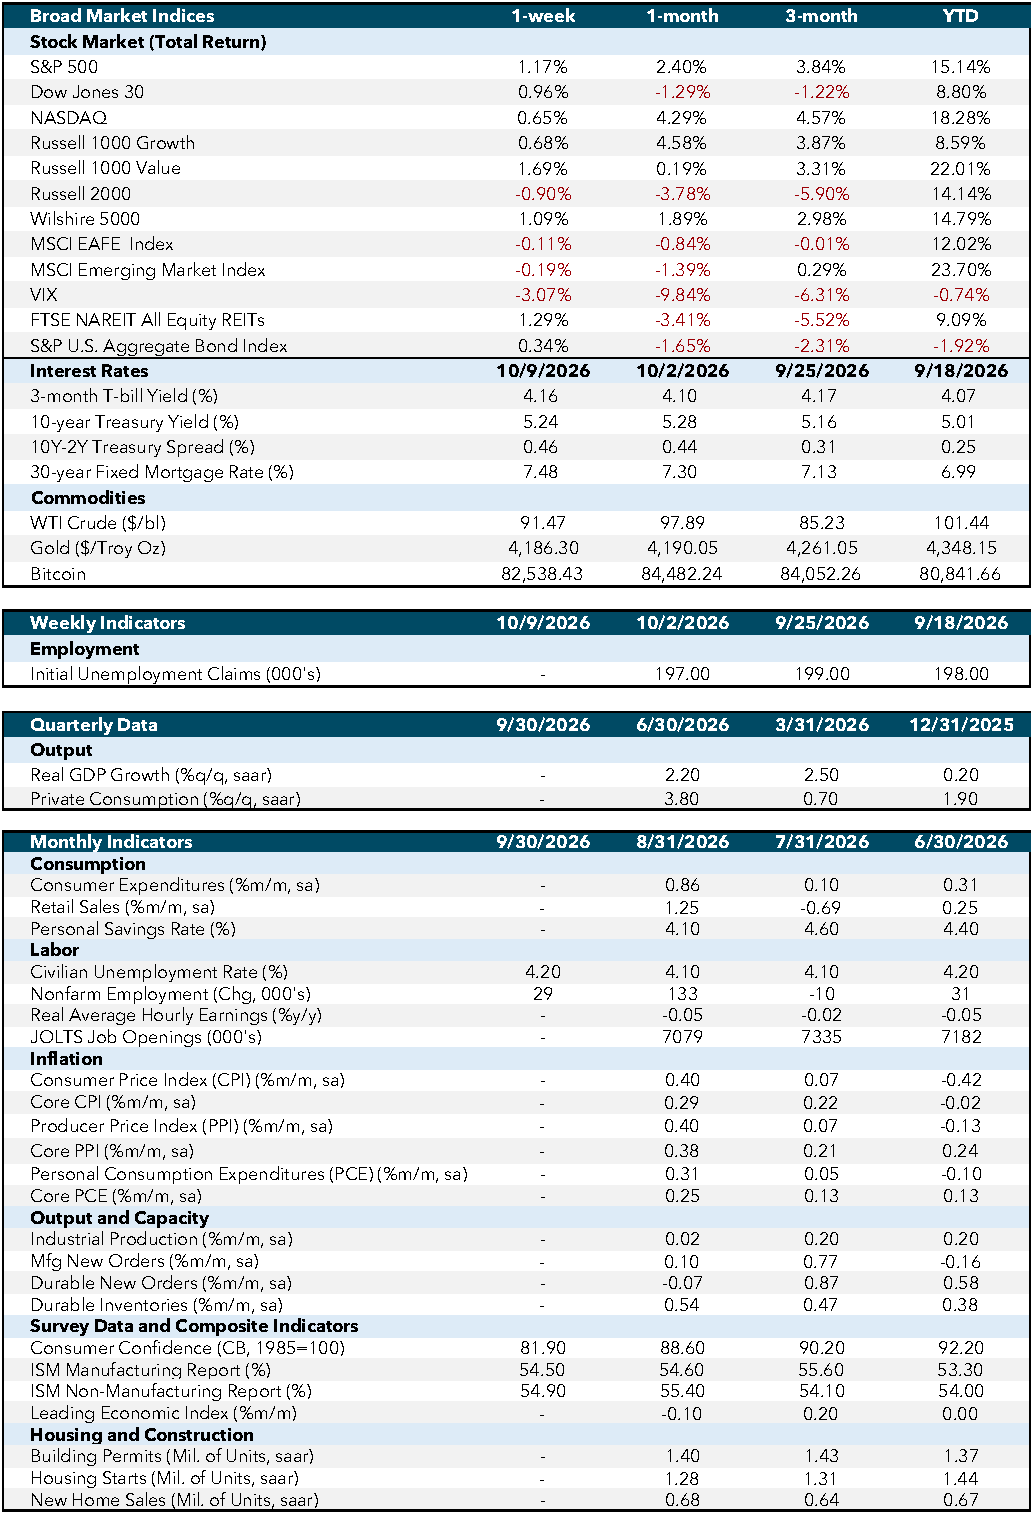
Market Commentary | October 12th, 2026

Weekly Market Commentary

October 12th, 2026

Week in Review

The economic data last week continued to point to a resilient U.S. economy, although the latest readings showed some moderation in service-sector activity alongside continued price pressures.

Monday’s Services Purchasing Managers’ Index (PMI) came in at 58.8 in September, slightly above both the 58.7 forecast and the prior reading. The Institute for Supply Management (ISM) Non-Manufacturing PMI was somewhat softer, declining to 54.9 from 55.4 and coming in below the 55.1 forecast. Despite the slowdown in activity, the ISM Non-Manufacturing Prices Index increased to 74.0 from 72.6, exceeding expectations of 73.3. Taken together, the data showed continued expansion across the service economy, but with price pressures remaining elevated and potentially complicating the broader inflation outlook.

Wednesday’s crude oil inventory report showed inventories declining by 3.186 million barrels, a significant contrast to expectations for a 1.9-million-barrel increase and the prior week’s 922,000-barrel build. Treasury markets were also in focus, with the 10-year note auction clearing at 5.300%, up sharply from 4.834% at the previous auction. The higher auction yield reflected a notable move upward from the prior offering and kept longer-term interest rates in focus.

Thursday’s labor-market data remained relatively steady, with initial jobless claims coming in at 197,000, below the 200,000 forecast and slightly below the prior week’s 199,000 reading. Longer-term Treasury yields were also higher at auction, with the 30-year bond clearing at 5.618%, up from 5.308% previously.

Overall, the week’s data continued to show resilience across services and the labor market, while elevated service-sector pricing and higher Treasury auction yields remained important areas to monitor as investors evaluate the direction of inflation and broader economic conditions.

Economic and Capital Markets Dashboard

Week Ahead…

The week of October 12 will be highlighted by several important economic releases focused on inflation, consumer spending, labor market conditions, and housing activity. Inflation will likely remain the primary area of focus, with both Consumer Price Index (CPI) and Producer Price Index (PPI) providing investors with an updated look at whether price pressures are continuing to build heading further into the fourth quarter.

Wednesday’s CPI report is expected to show headline inflation rising 0.6% month over month and 3.6% year over year in September, up from 0.4% and 3.4% previously. Core CPI is expected to increase a more moderate 0.2%. The combination of headline and core inflation should help investors assess whether price pressures are becoming more widespread or remain concentrated in more volatile categories. Thursday’s PPI report will provide an additional look at inflationary pressures at the producer level.

Attention will also turn toward the health of the consumer and broader economy. Thursday’s retail sales report should provide insight into whether consumer spending remains resilient, while initial jobless claims will offer another timely measure of labor market conditions. The Philadelphia Fed Manufacturing Index will provide an update on manufacturing activity, while Tuesday’s existing home sales report should help investors gauge the strength of housing demand.

Crude oil inventory data will provide another look at energy market conditions, while Fed Governor Warsh is scheduled to speak Thursday. Investors will likely monitor the remarks for additional perspective on monetary policy and the economic outlook. Overall, the week should provide a broader read on whether economic conditions remain resilient while inflation continues to influence the outlook for interest rates.

Economic Indicators:

  1. CPI: Consumer Price Index measures the average change in prices paid by consumers for goods and services over time. Source: Bureau of Labor Statistics.
  2. Core CPI: Core Consumer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  3. PPI: Producer Price Index measures the average change in selling prices received by domestic producers for their output. Source: Bureau of Labor Statistics.
  4. Core PPI: Core Producer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  5. PCE: Personal Consumption Expenditures measure the average change in prices paid by consumers for goods and services. Source: Bureau of Economic Analysis.
  6. Core PCE: Core Personal Consumption Expenditures exclude food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Economic Analysis.
  7. Industrial Production: Measures the output of the industrial sector, including manufacturing, mining, and utilities. Source: Federal Reserve.
  8. Mfg New Orders: Measures the value of new orders placed with manufacturers for durable and non-durable goods. Source: Census Bureau.
  9. Durable New Orders: Measures the value of new orders placed with manufacturers of durable goods. Source: Census Bureau.
  10. Durable Inventories: Measures the value of inventories held by manufacturers for durable goods. Source: Census Bureau.
  11. Consumer Confidence (CB, 1985=100): Measures the degree of optimism that consumers feel about the overall state of the economy and their personal financial situation. Source: Conference Board.
  12. ISM Manufacturing Report: Measures the economic health of the manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  13. ISM Non-Manufacturing Report: Measures the economic health of the non-manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  14. Leading Economic Index: Measures overall economic activity and predicts future economic trends. Source: Conference Board.
  15. Building Permits (Mil. of Units, saar): Measures the number of new residential building permits issued. Source: Census Bureau.
  16. Housing Starts (Mil. of Units, saar): Measures the number of new residential construction projects that have begun. Source: Census Bureau.
  17. New Home Sales (Mil. of Units, saar): Measures the number of newly constructed homes sold. Source: Census Bureau.
  18. SA: Seasonally adjusted.
  19. SAAR: Seasonally adjusted annual rate.

Market Indices & Indicators:

  1. S&P 500: A market-capitalization-weighted index of 500 leading publicly traded companies in the U.S., widely regarded as one of the best gauges of large U.S. stocks and the stock market overall.
  2. Dow Jones 30: Also known as the Dow Jones Industrial Average, it tracks the share price performance of 30 large, publicly traded U.S. companies, serving as a barometer of the stock market and economy.
  3. NASDAQ: The world’s first electronic stock exchange, primarily listing technology giants and operating 29 markets globally.
  4. Russell 1000 Growth: Measures the performance of large-cap growth segment of the U.S. equity universe, including companies with higher price-to-book ratios and growth metrics.
  5. Russell 1000 Value: Measures the performance of large-cap value segment of the U.S. equity universe, including companies with lower price-to-book ratios and growth metrics.
  6. Russell 2000: A market index composed of 2,000 small-cap companies, widely used as a benchmark for small-cap mutual funds.
  7. Wilshire 5000: A market-capitalization-weighted index capturing the performance of all American stocks actively traded in the U.S., representing the broadest measure of the U.S. stock market.
  8. MSCI EAFE Index: An equity index capturing large and mid-cap representation across developed markets countries around the world, excluding the U.S. and Canada.
  9. MSCI Emerging Market Index: Captures large and mid-cap representation across emerging markets countries, covering approximately 85% of the free float-adjusted market capitalization in each country.
  10. VIX: The CBOE Volatility Index measures the market’s expectations for volatility over the coming 30 days, often referred to as the “fear gauge.”
  11. FTSE NAREIT All Equity REITs: Measures the performance of all publicly traded equity real estate investment trusts (REITs) listed in the U.S., excluding mortgage REITs.
  12. S&P U.S. Aggregate Bond Index: Represents the performance of the U.S. investment-grade bond market, including government, corporate, mortgage-backed, and asset-backed securities.
  13. 3-Month T-bill Yield (%): The yield on U.S. Treasury bills with a maturity of three months, reflecting short-term interest rates.
  14. 10-Year Treasury Yield (%): The yield on U.S. Treasury bonds with a maturity of ten years, reflecting long-term interest rates.
  15. 10Y-2Y Treasury Spread (%): The difference between the yields on 10-year and 2-year U.S. Treasury bonds, often used as an indicator of economic expectations.
  16. WTI Crude ($/bl): The price per barrel of West Texas Intermediate crude oil, a benchmark for U.S. oil prices.
  17. Gold ($/Troy Oz): The price per troy ounce of gold, a standard measure for gold prices.
  18. Bitcoin: A decentralized digital currency without a central bank or single administrator, which can be sent from user to user on the peer-to-peer bitcoin network.

This content was developed by Cambridge and BridgePort from sources believed to be reliable. This content is provided for informational purposes only and should not be construed or acted upon as individualized investment advice. It should not be considered a recommendation or solicitation. Information is subject to change. Any forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. The information in this material is not intended as tax or legal advice.

Investing involves risk. Depending on the different types of investments there may be varying degrees of risk. Socially responsible investing does not guarantee any amount of success. Clients and prospective clients should be prepared to bear investment loss including loss of original principal. Indices mentioned are unmanaged and cannot be invested into directly. Past performance is not a guarantee of future results.

The Dow Jones Industrial Average (DJIA) is a price-weighted index composed of 30 widely traded blue-chip U.S. common stocks. The S&P 500 is a market-cap weighted index composed of the common stocks of 500 leading companies in leading industries of the U.S. economy. The NASDAQ Composite Index is a market-value weighted index of all common stocks listed on the NASDAQ stock exchange.

Securities offered through Cambridge Investment Research, Inc., a broker-dealer, member FINRA/SIPC, and investment advisory services offered through Cambridge Investment Research Advisors, Inc., a Registered Investment Adviser. BridgePort Financial Solutions, LLC is a Registered Investment Adviser with the U.S. Securities & Exchange Commission. All three are wholly-owned subsidiaries of Cambridge Investment Group, Inc. V.CIR.1026-3801