Market Commentary | October 12th, 2026

Weekly Market Commentary

October 12th, 2026

Week in Review

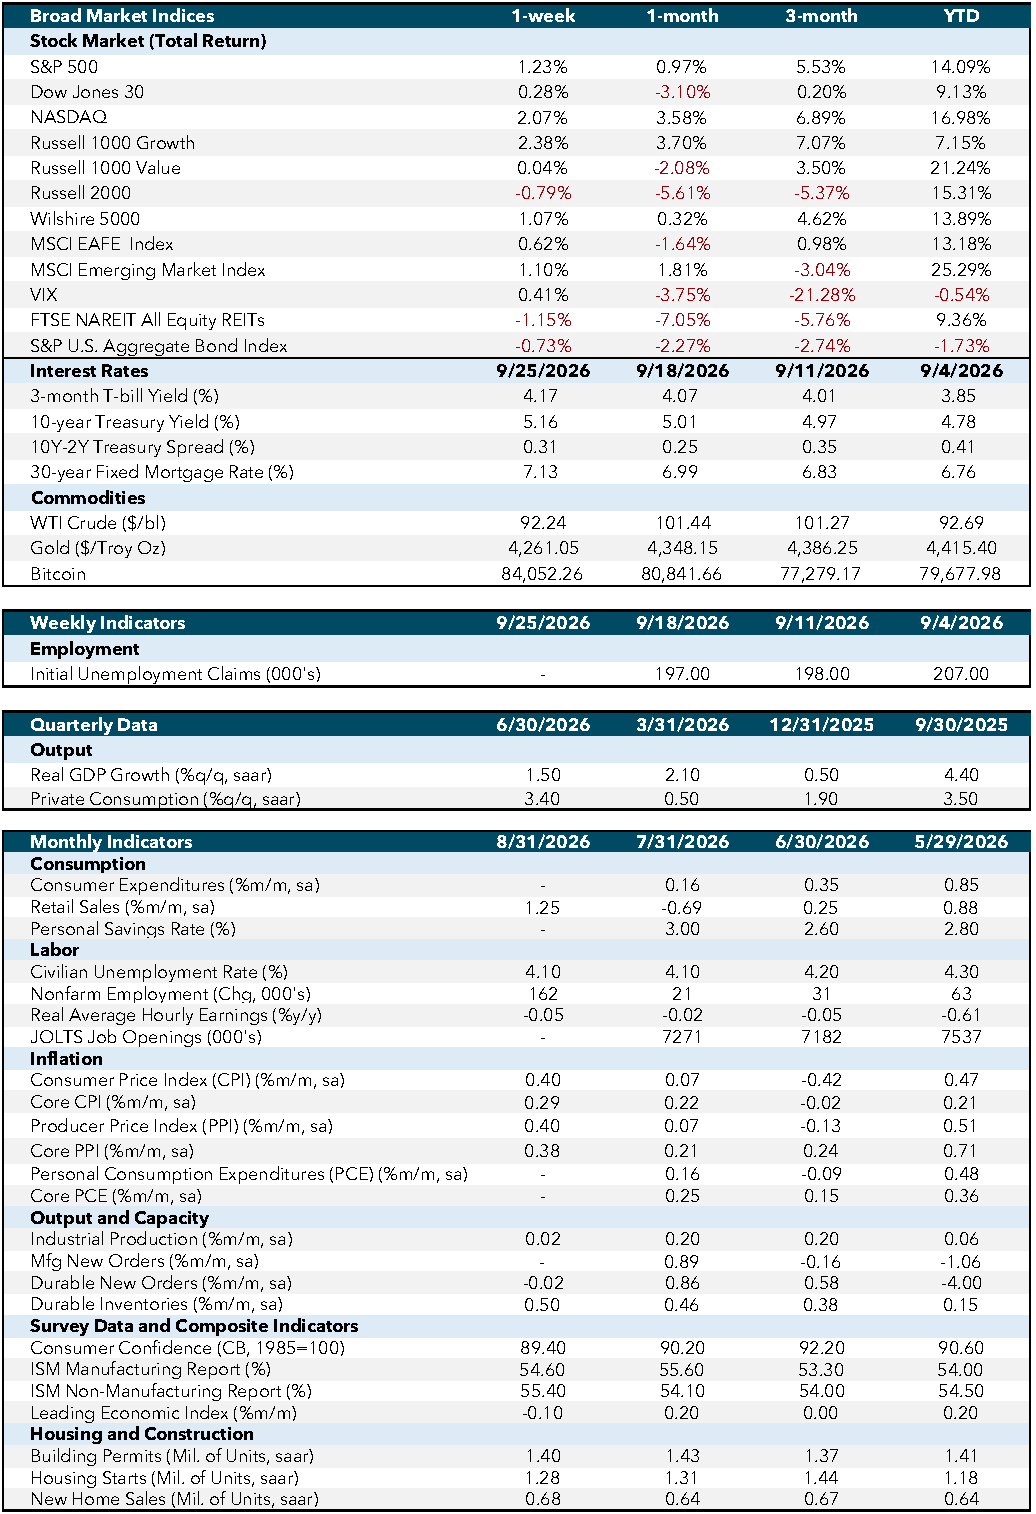
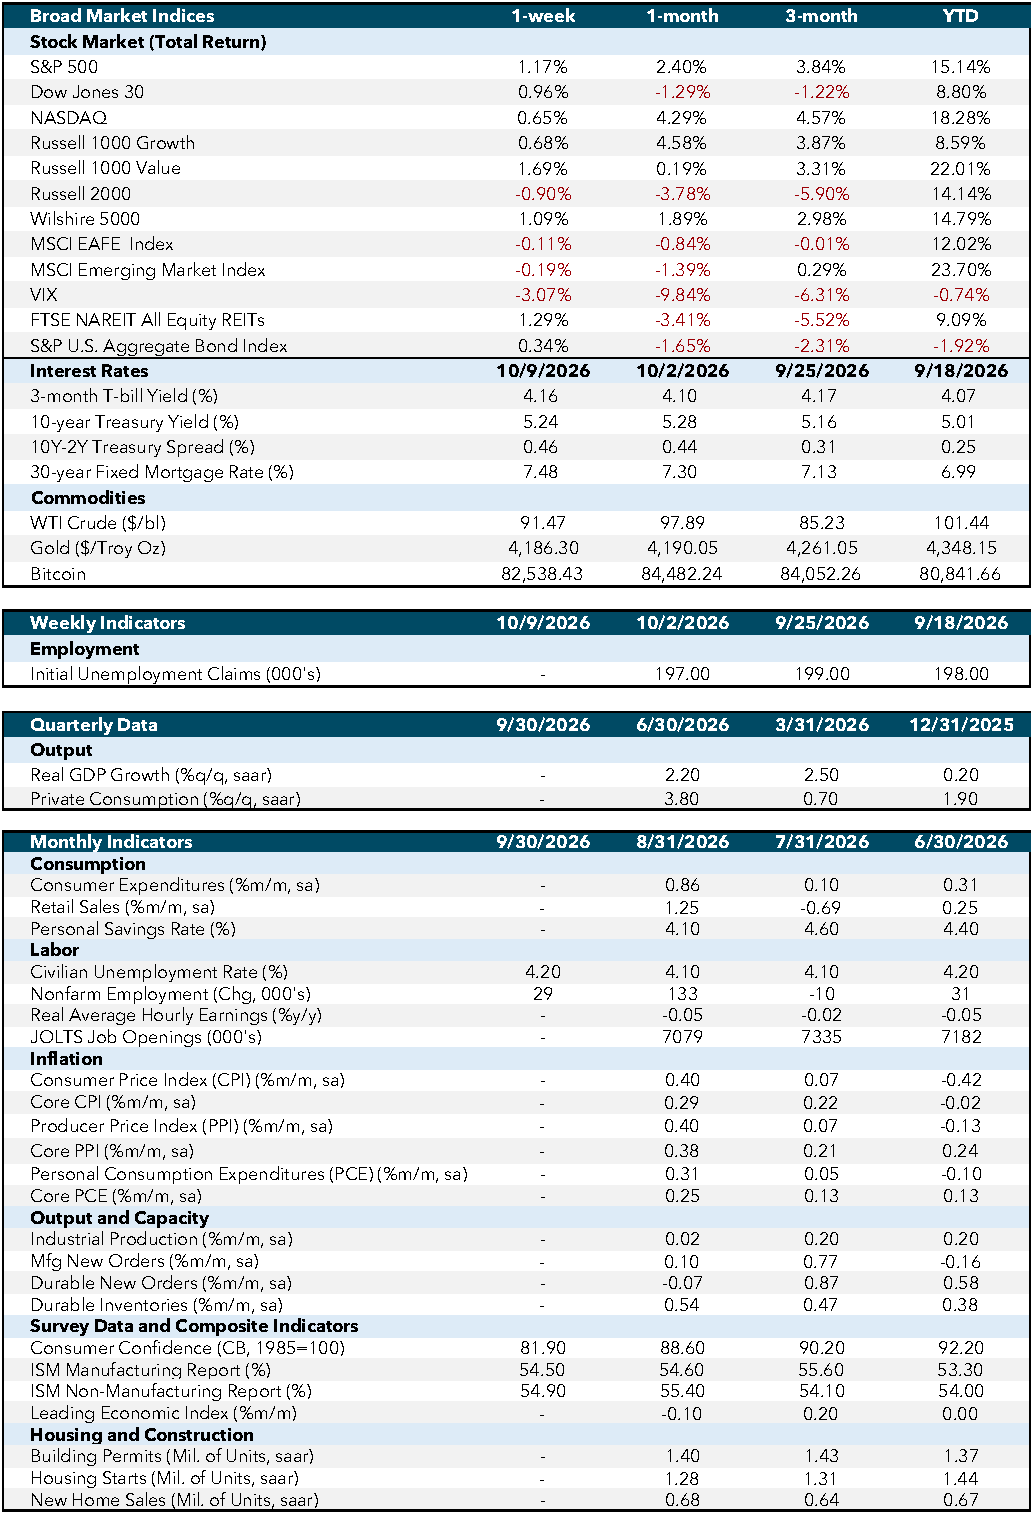
The economic data last week continued to point to a resilient U.S. economy, although the latest readings showed some moderation in service-sector activity alongside continued price pressures.

Monday’s Services Purchasing Managers’ Index (PMI) came in at 58.8 in September, slightly above both the 58.7 forecast and the prior reading. The Institute for Supply Management (ISM) Non-Manufacturing PMI was somewhat softer, declining to 54.9 from 55.4 and coming in below the 55.1 forecast. Despite the slowdown in activity, the ISM Non-Manufacturing Prices Index increased to 74.0 from 72.6, exceeding expectations of 73.3. Taken together, the data showed continued expansion across the service economy, but with price pressures remaining elevated and potentially complicating the broader inflation outlook.

Wednesday’s crude oil inventory report showed inventories declining by 3.186 million barrels, a significant contrast to expectations for a 1.9-million-barrel increase and the prior week’s 922,000-barrel build. Treasury markets were also in focus, with the 10-year note auction clearing at 5.300%, up sharply from 4.834% at the previous auction. The higher auction yield reflected a notable move upward from the prior offering and kept longer-term interest rates in focus.

Thursday’s labor-market data remained relatively steady, with initial jobless claims coming in at 197,000, below the 200,000 forecast and slightly below the prior week’s 199,000 reading. Longer-term Treasury yields were also higher at auction, with the 30-year bond clearing at 5.618%, up from 5.308% previously.

Overall, the week’s data continued to show resilience across services and the labor market, while elevated service-sector pricing and higher Treasury auction yields remained important areas to monitor as investors evaluate the direction of inflation and broader economic conditions.

Economic and Capital Markets Dashboard
Week Ahead…

The week of October 12 will be highlighted by several important economic releases focused on inflation, consumer spending, labor market conditions, and housing activity. Inflation will likely remain the primary area of focus, with both Consumer Price Index (CPI) and Producer Price Index (PPI) providing investors with an updated look at whether price pressures are continuing to build heading further into the fourth quarter.

Wednesday’s CPI report is expected to show headline inflation rising 0.6% month over month and 3.6% year over year in September, up from 0.4% and 3.4% previously. Core CPI is expected to increase a more moderate 0.2%. The combination of headline and core inflation should help investors assess whether price pressures are becoming more widespread or remain concentrated in more volatile categories. Thursday’s PPI report will provide an additional look at inflationary pressures at the producer level.

Attention will also turn toward the health of the consumer and broader economy. Thursday’s retail sales report should provide insight into whether consumer spending remains resilient, while initial jobless claims will offer another timely measure of labor market conditions. The Philadelphia Fed Manufacturing Index will provide an update on manufacturing activity, while Tuesday’s existing home sales report should help investors gauge the strength of housing demand.

Crude oil inventory data will provide another look at energy market conditions, while Fed Governor Warsh is scheduled to speak Thursday. Investors will likely monitor the remarks for additional perspective on monetary policy and the economic outlook. Overall, the week should provide a broader read on whether economic conditions remain resilient while inflation continues to influence the outlook for interest rates.

Economic Indicators:

  1. CPI: Consumer Price Index measures the average change in prices paid by consumers for goods and services over time. Source: Bureau of Labor Statistics.
  2. Core CPI: Core Consumer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  3. PPI: Producer Price Index measures the average change in selling prices received by domestic producers for their output. Source: Bureau of Labor Statistics.
  4. Core PPI: Core Producer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  5. PCE: Personal Consumption Expenditures measure the average change in prices paid by consumers for goods and services. Source: Bureau of Economic Analysis.
  6. Core PCE: Core Personal Consumption Expenditures exclude food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Economic Analysis.
  7. Industrial Production: Measures the output of the industrial sector, including manufacturing, mining, and utilities. Source: Federal Reserve.
  8. Mfg New Orders: Measures the value of new orders placed with manufacturers for durable and non-durable goods. Source: Census Bureau.
  9. Durable New Orders: Measures the value of new orders placed with manufacturers of durable goods. Source: Census Bureau.
  10. Durable Inventories: Measures the value of inventories held by manufacturers for durable goods. Source: Census Bureau.
  11. Consumer Confidence (CB, 1985=100): Measures the degree of optimism that consumers feel about the overall state of the economy and their personal financial situation. Source: Conference Board.
  12. ISM Manufacturing Report: Measures the economic health of the manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  13. ISM Non-Manufacturing Report: Measures the economic health of the non-manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  14. Leading Economic Index: Measures overall economic activity and predicts future economic trends. Source: Conference Board.
  15. Building Permits (Mil. of Units, saar): Measures the number of new residential building permits issued. Source: Census Bureau.
  16. Housing Starts (Mil. of Units, saar): Measures the number of new residential construction projects that have begun. Source: Census Bureau.
  17. New Home Sales (Mil. of Units, saar): Measures the number of newly constructed homes sold. Source: Census Bureau.
  18. SA: Seasonally adjusted.
  19. SAAR: Seasonally adjusted annual rate.

Market Indices & Indicators:

  1. S&P 500: A market-capitalization-weighted index of 500 leading publicly traded companies in the U.S., widely regarded as one of the best gauges of large U.S. stocks and the stock market overall.
  2. Dow Jones 30: Also known as the Dow Jones Industrial Average, it tracks the share price performance of 30 large, publicly traded U.S. companies, serving as a barometer of the stock market and economy.
  3. NASDAQ: The world’s first electronic stock exchange, primarily listing technology giants and operating 29 markets globally.
  4. Russell 1000 Growth: Measures the performance of large-cap growth segment of the U.S. equity universe, including companies with higher price-to-book ratios and growth metrics.
  5. Russell 1000 Value: Measures the performance of large-cap value segment of the U.S. equity universe, including companies with lower price-to-book ratios and growth metrics.
  6. Russell 2000: A market index composed of 2,000 small-cap companies, widely used as a benchmark for small-cap mutual funds.
  7. Wilshire 5000: A market-capitalization-weighted index capturing the performance of all American stocks actively traded in the U.S., representing the broadest measure of the U.S. stock market.
  8. MSCI EAFE Index: An equity index capturing large and mid-cap representation across developed markets countries around the world, excluding the U.S. and Canada.
  9. MSCI Emerging Market Index: Captures large and mid-cap representation across emerging markets countries, covering approximately 85% of the free float-adjusted market capitalization in each country.
  10. VIX: The CBOE Volatility Index measures the market’s expectations for volatility over the coming 30 days, often referred to as the “fear gauge.”
  11. FTSE NAREIT All Equity REITs: Measures the performance of all publicly traded equity real estate investment trusts (REITs) listed in the U.S., excluding mortgage REITs.
  12. S&P U.S. Aggregate Bond Index: Represents the performance of the U.S. investment-grade bond market, including government, corporate, mortgage-backed, and asset-backed securities.
  13. 3-Month T-bill Yield (%): The yield on U.S. Treasury bills with a maturity of three months, reflecting short-term interest rates.
  14. 10-Year Treasury Yield (%): The yield on U.S. Treasury bonds with a maturity of ten years, reflecting long-term interest rates.
  15. 10Y-2Y Treasury Spread (%): The difference between the yields on 10-year and 2-year U.S. Treasury bonds, often used as an indicator of economic expectations.
  16. WTI Crude ($/bl): The price per barrel of West Texas Intermediate crude oil, a benchmark for U.S. oil prices.
  17. Gold ($/Troy Oz): The price per troy ounce of gold, a standard measure for gold prices.
  18. Bitcoin: A decentralized digital currency without a central bank or single administrator, which can be sent from user to user on the peer-to-peer bitcoin network.

This content was developed by Cambridge and BridgePort from sources believed to be reliable. This content is provided for informational purposes only and should not be construed or acted upon as individualized investment advice. It should not be considered a recommendation or solicitation. Information is subject to change. Any forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. The information in this material is not intended as tax or legal advice.

Investing involves risk. Depending on the different types of investments there may be varying degrees of risk. Socially responsible investing does not guarantee any amount of success. Clients and prospective clients should be prepared to bear investment loss including loss of original principal. Indices mentioned are unmanaged and cannot be invested into directly. Past performance is not a guarantee of future results.

The Dow Jones Industrial Average (DJIA) is a price-weighted index composed of 30 widely traded blue-chip U.S. common stocks. The S&P 500 is a market-cap weighted index composed of the common stocks of 500 leading companies in leading industries of the U.S. economy. The NASDAQ Composite Index is a market-value weighted index of all common stocks listed on the NASDAQ stock exchange.

Securities offered through Cambridge Investment Research, Inc., a broker-dealer, member FINRA/SIPC, and investment advisory services offered through Cambridge Investment Research Advisors, Inc., a Registered Investment Adviser. BridgePort Financial Solutions, LLC is a Registered Investment Adviser with the U.S. Securities & Exchange Commission. All three are wholly-owned subsidiaries of Cambridge Investment Group, Inc. V.CIR.1026-3801
Market Commentary | October 5th, 2026

Market Commentary | October 5th, 2026

Weekly Market Commentary

October 5th, 2026

Week in Review

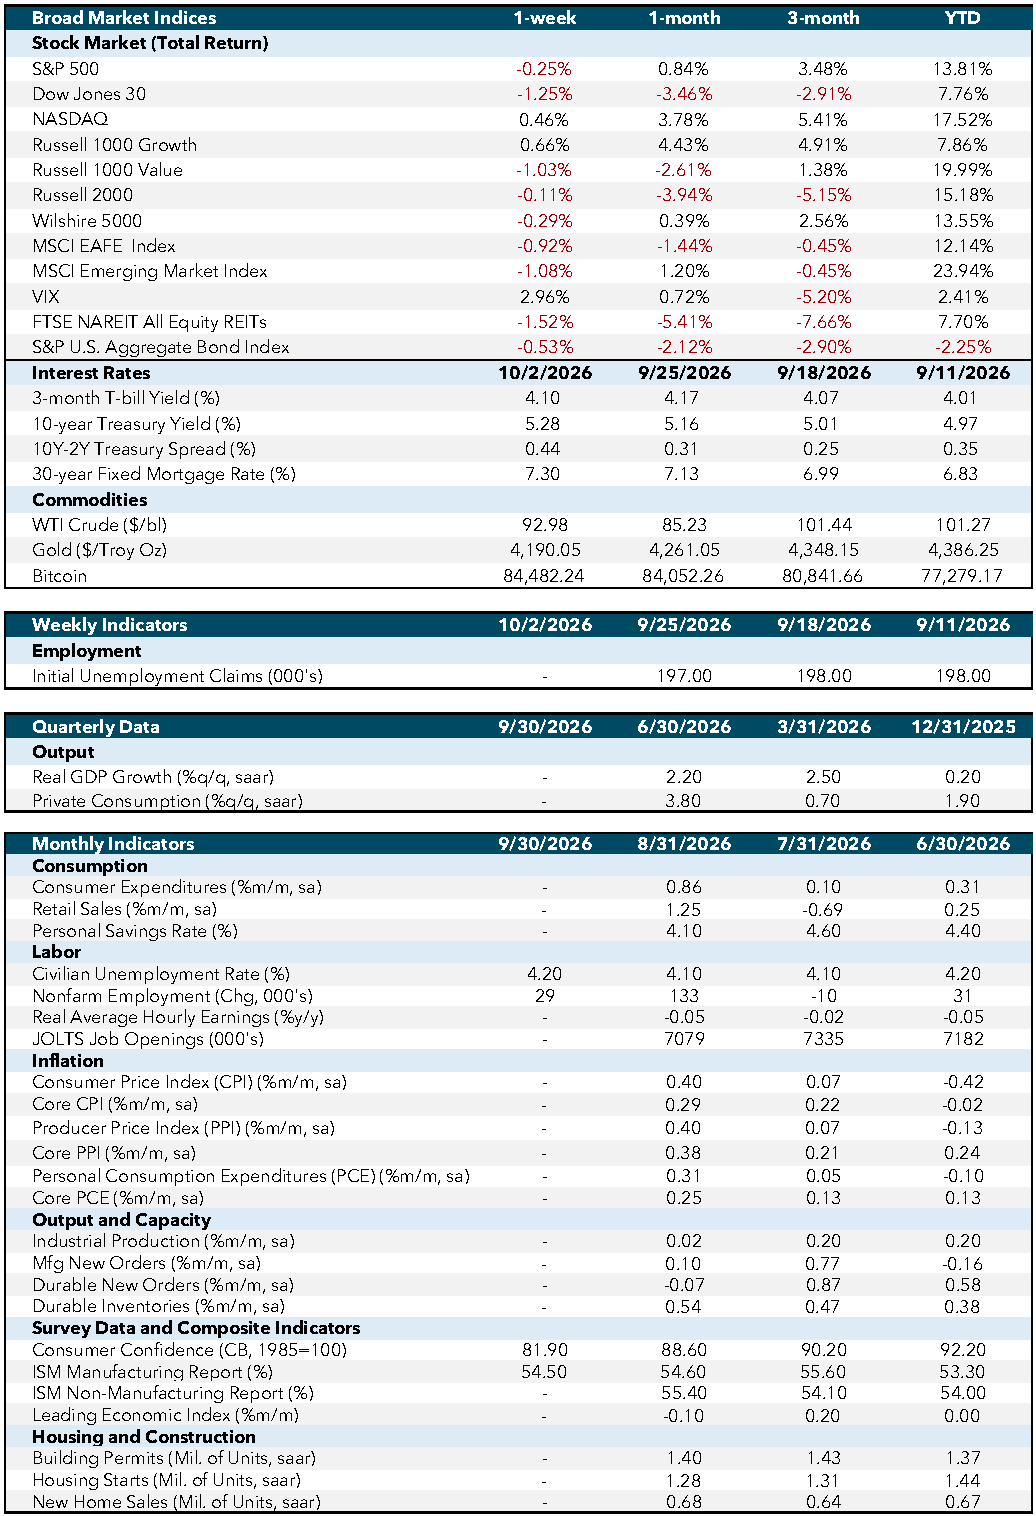
Inflation came in below expectations and Q2 U.S. gross domestic product (GDP) growth exceeded forecasts, while labor data pointed to slower hiring. Together, the releases showed continued economic expansion alongside moderating labor demand and inflation above the Federal Reserve’s target.

Inflation: Softer Than Expected but Still Above Target

Personal consumption expenditures (PCE) data, the Federal Reserve’s preferred inflation gauge, came in softer than expected for August. Headline PCE rose 0.3% month over month versus an expected 0.4%, and 3.4% year over year versus an expected 3.7%. Core PCE, which excludes more volatile food and energy costs, increased 0.2% month over month versus an expected 0.3%, and 3.0% year over year versus an expected 3.3%. The data reflect price increases in other nondurable goods, gas and energy goods, and food services, which were the largest increases. The updated figures reflect the Bureau of Economic Analysis’ revisions to how it calculates the index, including changes to price measurements for legal services, software, and portfolio management.

Despite the softer readings, the figures continue to show that inflation remains above the Fed’s 2% target. The Fed raised rates by 0.25 percentage points in September to a range of 3.75%-4.00%, with markets predicting a 78% chance that the Fed remains on hold at the next October meeting.

Economic Activity: Growth and Manufacturing Remain Firm

Second-quarter real GDP grew at a 2.2% annualized rate versus an expected 1.5%, supported by consumer spending, business investment, and exports, while higher imports were a headwind. Separately, the Institute for Supply Management® (ISM) Manufacturing Purchasing Managers’ Index® (PMI) eased to 54.5 versus an expected 54.8, but remained above the expansion threshold of 50. New orders, production, employment, and supplier deliveries remained in expansion territory, while the prices component jumped as a result of tightening supply amid respondents’ concerns of higher costs due to tariffs and the war in Iran.

Labor Market: Hiring Slows as Layoffs Remain Limited

September non-farm payrolls surprised sharply to the downside with 29,000 jobs added versus an expected 89,000, down from 133,000 in August. Unemployment edged up to 4.2% versus an expected 4.1%. Job Openings and Labor Turnover Survey (JOLTS) openings declined to 7.079 million from 7.335 million and were below the 7.230 million estimate. Initial jobless claims were 197,000 versus an expected 201,000, and continuing claims were down to 1.701 million versus an expected 1.730 million. The figures point to slower hiring while layoffs remained contained, consistent with a “low hire, low fire” environment.

Economic and Capital Markets Dashboard

Week Ahead…

The coming week will provide updates on service-sector activity and the Federal Reserve’s policy discussions.

Services Activity: Monitoring the Pass-Through of Higher Prices

Markets will look to the ISM Services PMI for evidence that service-sector activity remains in expansion. The report will provide additional context on how higher prices are feeding into the service sector.

Federal Reserve: Assessing the Path for Further Rate Hikes

The Federal Open Market Committee (FOMC) minutes will provide details on how policymakers assessed inflation, employment, and the potential path of rate hikes through year-end. Markets will focus on commentary about further rate hikes as recent cooler inflation and employment data shape expectations.

Economic Indicators:

  1. CPI: Consumer Price Index measures the average change in prices paid by consumers for goods and services over time. Source: Bureau of Labor Statistics.
  2. Core CPI: Core Consumer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  3. PPI: Producer Price Index measures the average change in selling prices received by domestic producers for their output. Source: Bureau of Labor Statistics.
  4. Core PPI: Core Producer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  5. PCE: Personal Consumption Expenditures measure the average change in prices paid by consumers for goods and services. Source: Bureau of Economic Analysis.
  6. Core PCE: Core Personal Consumption Expenditures exclude food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Economic Analysis.
  7. Industrial Production: Measures the output of the industrial sector, including manufacturing, mining, and utilities. Source: Federal Reserve.
  8. Mfg New Orders: Measures the value of new orders placed with manufacturers for durable and non-durable goods. Source: Census Bureau.
  9. Durable New Orders: Measures the value of new orders placed with manufacturers of durable goods. Source: Census Bureau.
  10. Durable Inventories: Measures the value of inventories held by manufacturers for durable goods. Source: Census Bureau.
  11. Consumer Confidence (CB, 1985=100): Measures the degree of optimism that consumers feel about the overall state of the economy and their personal financial situation. Source: Conference Board.
  12. ISM Manufacturing Report: Measures the economic health of the manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  13. ISM Non-Manufacturing Report: Measures the economic health of the non-manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  14. Leading Economic Index: Measures overall economic activity and predicts future economic trends. Source: Conference Board.
  15. Building Permits (Mil. of Units, saar): Measures the number of new residential building permits issued. Source: Census Bureau.
  16. Housing Starts (Mil. of Units, saar): Measures the number of new residential construction projects that have begun. Source: Census Bureau.
  17. New Home Sales (Mil. of Units, saar): Measures the number of newly constructed homes sold. Source: Census Bureau.
  18. SA: Seasonally adjusted.
  19. SAAR: Seasonally adjusted annual rate.

Market Indices & Indicators:

  1. S&P 500: A market-capitalization-weighted index of 500 leading publicly traded companies in the U.S., widely regarded as one of the best gauges of large U.S. stocks and the stock market overall.
  2. Dow Jones 30: Also known as the Dow Jones Industrial Average, it tracks the share price performance of 30 large, publicly traded U.S. companies, serving as a barometer of the stock market and economy.
  3. NASDAQ: The world’s first electronic stock exchange, primarily listing technology giants and operating 29 markets globally.
  4. Russell 1000 Growth: Measures the performance of large-cap growth segment of the U.S. equity universe, including companies with higher price-to-book ratios and growth metrics.
  5. Russell 1000 Value: Measures the performance of large-cap value segment of the U.S. equity universe, including companies with lower price-to-book ratios and growth metrics.
  6. Russell 2000: A market index composed of 2,000 small-cap companies, widely used as a benchmark for small-cap mutual funds.
  7. Wilshire 5000: A market-capitalization-weighted index capturing the performance of all American stocks actively traded in the U.S., representing the broadest measure of the U.S. stock market.
  8. MSCI EAFE Index: An equity index capturing large and mid-cap representation across developed markets countries around the world, excluding the U.S. and Canada.
  9. MSCI Emerging Market Index: Captures large and mid-cap representation across emerging markets countries, covering approximately 85% of the free float-adjusted market capitalization in each country.
  10. VIX: The CBOE Volatility Index measures the market’s expectations for volatility over the coming 30 days, often referred to as the “fear gauge.”
  11. FTSE NAREIT All Equity REITs: Measures the performance of all publicly traded equity real estate investment trusts (REITs) listed in the U.S., excluding mortgage REITs.
  12. S&P U.S. Aggregate Bond Index: Represents the performance of the U.S. investment-grade bond market, including government, corporate, mortgage-backed, and asset-backed securities.
  13. 3-Month T-bill Yield (%): The yield on U.S. Treasury bills with a maturity of three months, reflecting short-term interest rates.
  14. 10-Year Treasury Yield (%): The yield on U.S. Treasury bonds with a maturity of ten years, reflecting long-term interest rates.
  15. 10Y-2Y Treasury Spread (%): The difference between the yields on 10-year and 2-year U.S. Treasury bonds, often used as an indicator of economic expectations.
  16. WTI Crude ($/bl): The price per barrel of West Texas Intermediate crude oil, a benchmark for U.S. oil prices.
  17. Gold ($/Troy Oz): The price per troy ounce of gold, a standard measure for gold prices.
  18. Bitcoin: A decentralized digital currency without a central bank or single administrator, which can be sent from user to user on the peer-to-peer bitcoin network.

This content was developed by Cambridge from sources believed to be reliable. This content is provided for informational purposes only and should not be construed or acted upon as individualized investment advice. It should not be considered a recommendation or solicitation. Information is subject to change. Any forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. The information in this material is not intended as tax or legal advice.

Investing involves risk. Depending on the different types of investments there may be varying degrees of risk. Socially responsible investing does not guarantee any amount of success. Clients and prospective clients should be prepared to bear investment loss including loss of original principal. Indices mentioned are unmanaged and cannot be invested into directly. Past performance is not a guarantee of future results.

The Dow Jones Industrial Average (DJIA) is a price-weighted index composed of 30 widely traded blue-chip U.S. common stocks. The S&P 500 is a market-cap weighted index composed of the common stocks of 500 leading companies in leading industries of the U.S. economy. The NASDAQ Composite Index is a market-value weighted index of all common stocks listed on the NASDAQ stock exchange.

Securities offered through Cambridge Investment Research, Inc., a broker-dealer, member FINRA/SIPC, and investment advisory services offered through Cambridge Investment Research Advisors, Inc., a Registered Investment Adviser. Both are wholly-owned subsidiaries of Cambridge Investment Group, Inc. V.CIR.1026-3697

Market Commentary | September 28th, 2026

Weekly Market Commentary

September 28th, 2026

Week in Review

Business sentiment surged to multiyear highs while labor market data continued to improve. However, several hard economic indicators have yet to fully confirm the growing optimism, creating an increasingly important question for investors heading into the fourth quarter.

Business Sentiment: Optimism Builds, but Confirmation Is Needed

Preliminary S&P Global Purchasing Managers’ Index (PMI) data offered an unexpectedly strong view of business conditions. Manufacturing PMI rose to 57.0 from 53.9, marking a third consecutive upside surprise and its highest reading in more than four years. Services PMI strengthened to 58.7 from 56.5, reaching a multiyear high. Together, the reports suggest momentum may be broadening across the economy rather than remaining concentrated in one sector.

The strength in services is particularly important given the sector’s outsized contribution to economic activity. However, investors will likely temper their optimism because the reports are preliminary and subject to revision. Final readings will help determine whether September marked a genuine acceleration or an unusually strong initial sample.

Consumer data provided a useful counterweight. The University of Michigan’s Consumer Sentiment and Expectations indexes exceeded forecasts but declined from August, suggesting households remain more cautious than businesses. The divergence does not invalidate the PMI strength, but it indicates the improvement in confidence is not yet uniform across the economy.

Hard Data: Optimism Has Yet to Fully Translate

Housing and capital spending data painted a more measured picture. August’s building permits exceeded expectations (1.403 million versus 1.394 million) but declined from the prior month (1.433 million). The August reading was also broadly consistent with May, suggesting the sharp June decline and July rebound may have reflected monthly noise rather than a clear change in direction.

Core durable goods orders rose by just 0.3% versus the 0.6% expected, signaling that businesses have not yet translated stronger sentiment into equally strong capital spending. The timing of the reports may partly explain the disconnect. Still, markets will want to see hard activity strengthen before concluding that the recent PMI acceleration represents a durable change in momentum.

Labor Market: Claims Point to Greater Stability

Jobless claims remained constructive. Continuing claims fell to 1.730 million, below the 1.780 million forecast, marking a third consecutive better-than-expected reading and extending a broader decline from the summer’s higher levels.

Initial claims also fell below 200,000, while the four-week average declined to 202,250 from approximately 224,000 in June. Weekly fluctuations remain common, but the broader trend suggests layoffs are becoming less frequent and the labor market remains more stable than recent growth concerns might imply.

Economic and Capital Markets Dashboard

Week Ahead…

This week’s economic calendar will provide investors with an important update on the labor market, business sentiment, and inflation. Following last week’s strong PMI reports and improving jobless claims data, markets will be looking for confirmation that recent optimism is beginning to translate into broader economic activity.

Labor Market: A Closer Look Beneath the Headline

Labor market data will take center stage this week. Tuesday’s Job Openings and Labor Turnover Survey (JOLTS) report will provide additional insight into labor market dynamics, particularly the balance between labor supply and demand. Investors will pay close attention to job openings and the quits rate, as higher voluntary job turnover can indicate workers remain confident in their ability to find new employment opportunities.

The week’s most closely watched release will arrive Friday with the September Employment Report. While nonfarm payrolls and the unemployment rate will receive the greatest attention, markets will also monitor measures such as labor force participation and the broader U-6 unemployment rate for clues about the labor market’s underlying health. Following recent improvements in jobless claims, investors will be looking to see whether payroll growth continues to support the view that labor conditions remain resilient.

Business Sentiment: Looking for Confirmation

Markets will also receive Institute for Supply Management (ISM) Manufacturing and ISM Services data, providing an opportunity to validate the strong S&P Global PMI readings released last week. Particular attention will be paid to whether the ISM surveys reflect a similar improvement in business sentiment across both sectors of the economy.

Confirmation from the ISM reports would strengthen the case that business confidence is improving more broadly rather than being isolated to a single survey provider.

Inflation: Focus Remains on Core PCE

Wednesday’s Core Personal Consumption Expenditures (PCE) report will provide the latest update on inflation trends. Although Core PCE has historically served as the Federal Reserve’s preferred inflation measure, investors may place somewhat less emphasis on the report as policymakers have recently referenced a broader range of inflation indicators. Nevertheless, any meaningful surprise could influence expectations surrounding the future path of monetary policy.

Economic Indicators:

  1. CPI: Consumer Price Index measures the average change in prices paid by consumers for goods and services over time. Source: Bureau of Labor Statistics.
  2. Core CPI: Core Consumer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  3. PPI: Producer Price Index measures the average change in selling prices received by domestic producers for their output. Source: Bureau of Labor Statistics.
  4. Core PPI: Core Producer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  5. PCE: Personal Consumption Expenditures measure the average change in prices paid by consumers for goods and services. Source: Bureau of Economic Analysis.
  6. Core PCE: Core Personal Consumption Expenditures exclude food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Economic Analysis.
  7. Industrial Production: Measures the output of the industrial sector, including manufacturing, mining, and utilities. Source: Federal Reserve.
  8. Mfg New Orders: Measures the value of new orders placed with manufacturers for durable and non-durable goods. Source: Census Bureau.
  9. Durable New Orders: Measures the value of new orders placed with manufacturers of durable goods. Source: Census Bureau.
  10. Durable Inventories: Measures the value of inventories held by manufacturers for durable goods. Source: Census Bureau.
  11. Consumer Confidence (CB, 1985=100): Measures the degree of optimism that consumers feel about the overall state of the economy and their personal financial situation. Source: Conference Board.
  12. ISM Manufacturing Report: Measures the economic health of the manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  13. ISM Non-Manufacturing Report: Measures the economic health of the non-manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  14. Leading Economic Index: Measures overall economic activity and predicts future economic trends. Source: Conference Board.
  15. Building Permits (Mil. of Units, saar): Measures the number of new residential building permits issued. Source: Census Bureau.
  16. Housing Starts (Mil. of Units, saar): Measures the number of new residential construction projects that have begun. Source: Census Bureau.
  17. New Home Sales (Mil. of Units, saar): Measures the number of newly constructed homes sold. Source: Census Bureau.
  18. SA: Seasonally adjusted.
  19. SAAR: Seasonally adjusted annual rate.

Market Indices & Indicators:

  1. S&P 500: A market-capitalization-weighted index of 500 leading publicly traded companies in the U.S., widely regarded as one of the best gauges of large U.S. stocks and the stock market overall.
  2. Dow Jones 30: Also known as the Dow Jones Industrial Average, it tracks the share price performance of 30 large, publicly traded U.S. companies, serving as a barometer of the stock market and economy.
  3. NASDAQ: The world’s first electronic stock exchange, primarily listing technology giants and operating 29 markets globally.
  4. Russell 1000 Growth: Measures the performance of large-cap growth segment of the U.S. equity universe, including companies with higher price-to-book ratios and growth metrics.
  5. Russell 1000 Value: Measures the performance of large-cap value segment of the U.S. equity universe, including companies with lower price-to-book ratios and growth metrics.
  6. Russell 2000: A market index composed of 2,000 small-cap companies, widely used as a benchmark for small-cap mutual funds.
  7. Wilshire 5000: A market-capitalization-weighted index capturing the performance of all American stocks actively traded in the U.S., representing the broadest measure of the U.S. stock market.
  8. MSCI EAFE Index: An equity index capturing large and mid-cap representation across developed markets countries around the world, excluding the U.S. and Canada.
  9. MSCI Emerging Market Index: Captures large and mid-cap representation across emerging markets countries, covering approximately 85% of the free float-adjusted market capitalization in each country.
  10. VIX: The CBOE Volatility Index measures the market’s expectations for volatility over the coming 30 days, often referred to as the “fear gauge.”
  11. FTSE NAREIT All Equity REITs: Measures the performance of all publicly traded equity real estate investment trusts (REITs) listed in the U.S., excluding mortgage REITs.
  12. S&P U.S. Aggregate Bond Index: Represents the performance of the U.S. investment-grade bond market, including government, corporate, mortgage-backed, and asset-backed securities.
  13. 3-Month T-bill Yield (%): The yield on U.S. Treasury bills with a maturity of three months, reflecting short-term interest rates.
  14. 10-Year Treasury Yield (%): The yield on U.S. Treasury bonds with a maturity of ten years, reflecting long-term interest rates.
  15. 10Y-2Y Treasury Spread (%): The difference between the yields on 10-year and 2-year U.S. Treasury bonds, often used as an indicator of economic expectations.
  16. WTI Crude ($/bl): The price per barrel of West Texas Intermediate crude oil, a benchmark for U.S. oil prices.
  17. Gold ($/Troy Oz): The price per troy ounce of gold, a standard measure for gold prices.
  18. Bitcoin: A decentralized digital currency without a central bank or single administrator, which can be sent from user to user on the peer-to-peer bitcoin network.

This content was developed by Cambridge and BridgePort from sources believed to be reliable. This content is provided for informational purposes only and should not be construed or acted upon as individualized investment advice. It should not be considered a recommendation or solicitation. Information is subject to change. Any forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. The information in this material is not intended as tax or legal advice.

Investing involves risk. Depending on the different types of investments there may be varying degrees of risk. Socially responsible investing does not guarantee any amount of success. Clients and prospective clients should be prepared to bear investment loss including loss of original principal. Indices mentioned are unmanaged and cannot be invested into directly. Past performance is not a guarantee of future results.

The Dow Jones Industrial Average (DJIA) is a price-weighted index composed of 30 widely traded blue-chip U.S. common stocks. The S&P 500 is a market-cap weighted index composed of the common stocks of 500 leading companies in leading industries of the U.S. economy. The NASDAQ Composite Index is a market-value weighted index of all common stocks listed on the NASDAQ stock exchange.

Securities offered through Cambridge Investment Research, Inc., a broker-dealer, member FINRA/SIPC, and investment advisory services offered through Cambridge Investment Research Advisors, Inc., a Registered Investment Adviser. BridgePort Financial Solutions, LLC is a Registered Investment Adviser with the U.S. Securities & Exchange Commission. All three are wholly-owned subsidiaries of Cambridge Investment Group, Inc. V.CIR.0926-3605

Market Commentary | September 21st, 2026

Market Commentary | September 21st, 2026

Weekly Market Commentary

September 21st, 2026

Week in Review

Economic data last week continued to show a resilient U.S. economy, although the primary focus was the Federal Reserve’s September policy meeting and the inflation outlook. Treasury yields remained elevated throughout the week, with the 10-year Treasury finishing near 5.0% and the 30-year ending around 5.34%, as investors digested the Federal Reserve’s 25-basis-point rate increase and updated economic projections.

Wednesday’s retail sales report showed consumer spending remained strong despite higher borrowing costs and rising prices. Retail and food services sales increased 1.2% in August after declining 0.5% in July. Sales excluding autos rose 1.4%, suggesting household spending continues to support broader economic growth.

The Federal Reserve subsequently raised the federal funds target range by 25 basis points to 3.75% to 4.00%. Updated economic projections showed policymakers now expect stronger economic growth and somewhat higher inflation than previously anticipated. The median projection for the federal funds rate at year-end also increased, suggesting officials remain focused on returning inflation toward their long-term objective despite continued resilience in the broader economy.

Other economic data were more mixed. Housing starts declined 2.6% in August to a 1.275 million annualized pace, while building permits fell 2.7%, indicating that elevated financing costs continue to weigh on housing activity. Industrial production was unchanged during the month as softer manufacturing output was offset by stronger utility production. Consumer sentiment also weakened in September, with the preliminary University of Michigan Consumer Sentiment Index falling to 47.8 from 51.7 in August. Year-ahead inflation expectations increased to 4.6%, reflecting continued concerns about higher energy prices and broader inflation pressures.

Economic and Capital Markets Dashboard

Week Ahead…

The economic calendar will be lighter this week following the Federal Reserve meeting, but several reports should provide additional insight into the health of the consumer, housing market, and broader business activity. Markets will continue evaluating whether economic growth remains strong enough to support the Federal Reserve’s increasingly firm stance on inflation.

The first major release of the week will be September’s preliminary Purchasing Managers’ Indexes on Wednesday. The August manufacturing index stood at 53.9, while the services index was 56.5, both indicating continued expansion. Investors will be watching these surveys closely for evidence that higher energy prices and tighter financial conditions are beginning to affect business activity.

Attention will then turn to Thursday’s labor market and housing data. Initial jobless claims have remained near historically low levels, highlighting continued labor market strength. August new home sales will also be released Thursday morning and should provide another gauge of housing demand amid elevated mortgage rates and Treasury yields.

Friday’s August durable goods orders report will offer additional insight into manufacturing activity and business investment. Investors will also receive the final September reading of the University of Michigan consumer sentiment survey after the preliminary report showed weaker confidence and rising inflation expectations. Together, these releases should provide additional insight into the balance between economic growth and inflation and help shape expectations for the path of interest rates moving forward.

Economic Indicators:

  1. CPI: Consumer Price Index measures the average change in prices paid by consumers for goods and services over time. Source: Bureau of Labor Statistics.
  2. Core CPI: Core Consumer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  3. PPI: Producer Price Index measures the average change in selling prices received by domestic producers for their output. Source: Bureau of Labor Statistics.
  4. Core PPI: Core Producer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  5. PCE: Personal Consumption Expenditures measure the average change in prices paid by consumers for goods and services. Source: Bureau of Economic Analysis.
  6. Core PCE: Core Personal Consumption Expenditures exclude food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Economic Analysis.
  7. Industrial Production: Measures the output of the industrial sector, including manufacturing, mining, and utilities. Source: Federal Reserve.
  8. Mfg New Orders: Measures the value of new orders placed with manufacturers for durable and non-durable goods. Source: Census Bureau.
  9. Durable New Orders: Measures the value of new orders placed with manufacturers of durable goods. Source: Census Bureau.
  10. Durable Inventories: Measures the value of inventories held by manufacturers for durable goods. Source: Census Bureau.
  11. Consumer Confidence (CB, 1985=100): Measures the degree of optimism that consumers feel about the overall state of the economy and their personal financial situation. Source: Conference Board.
  12. ISM Manufacturing Report: Measures the economic health of the manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  13. ISM Non-Manufacturing Report: Measures the economic health of the non-manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  14. Leading Economic Index: Measures overall economic activity and predicts future economic trends. Source: Conference Board.
  15. Building Permits (Mil. of Units, saar): Measures the number of new residential building permits issued. Source: Census Bureau.
  16. Housing Starts (Mil. of Units, saar): Measures the number of new residential construction projects that have begun. Source: Census Bureau.
  17. New Home Sales (Mil. of Units, saar): Measures the number of newly constructed homes sold. Source: Census Bureau.
  18. SA: Seasonally adjusted.
  19. SAAR: Seasonally adjusted annual rate.

Market Indices & Indicators:

  1. S&P 500: A market-capitalization-weighted index of 500 leading publicly traded companies in the U.S., widely regarded as one of the best gauges of large U.S. stocks and the stock market overall.
  2. Dow Jones 30: Also known as the Dow Jones Industrial Average, it tracks the share price performance of 30 large, publicly traded U.S. companies, serving as a barometer of the stock market and economy.
  3. NASDAQ: The world’s first electronic stock exchange, primarily listing technology giants and operating 29 markets globally.
  4. Russell 1000 Growth: Measures the performance of large-cap growth segment of the U.S. equity universe, including companies with higher price-to-book ratios and growth metrics.
  5. Russell 1000 Value: Measures the performance of large-cap value segment of the U.S. equity universe, including companies with lower price-to-book ratios and growth metrics.
  6. Russell 2000: A market index composed of 2,000 small-cap companies, widely used as a benchmark for small-cap mutual funds.
  7. Wilshire 5000: A market-capitalization-weighted index capturing the performance of all American stocks actively traded in the U.S., representing the broadest measure of the U.S. stock market.
  8. MSCI EAFE Index: An equity index capturing large and mid-cap representation across developed markets countries around the world, excluding the U.S. and Canada.
  9. MSCI Emerging Market Index: Captures large and mid-cap representation across emerging markets countries, covering approximately 85% of the free float-adjusted market capitalization in each country.
  10. VIX: The CBOE Volatility Index measures the market’s expectations for volatility over the coming 30 days, often referred to as the “fear gauge.”
  11. FTSE NAREIT All Equity REITs: Measures the performance of all publicly traded equity real estate investment trusts (REITs) listed in the U.S., excluding mortgage REITs.
  12. S&P U.S. Aggregate Bond Index: Represents the performance of the U.S. investment-grade bond market, including government, corporate, mortgage-backed, and asset-backed securities.
  13. 3-Month T-bill Yield (%): The yield on U.S. Treasury bills with a maturity of three months, reflecting short-term interest rates.
  14. 10-Year Treasury Yield (%): The yield on U.S. Treasury bonds with a maturity of ten years, reflecting long-term interest rates.
  15. 10Y-2Y Treasury Spread (%): The difference between the yields on 10-year and 2-year U.S. Treasury bonds, often used as an indicator of economic expectations.
  16. WTI Crude ($/bl): The price per barrel of West Texas Intermediate crude oil, a benchmark for U.S. oil prices.
  17. Gold ($/Troy Oz): The price per troy ounce of gold, a standard measure for gold prices.
  18. Bitcoin: A decentralized digital currency without a central bank or single administrator, which can be sent from user to user on the peer-to-peer bitcoin network.

This content was developed by Cambridge from sources believed to be reliable. This content is provided for informational purposes only and should not be construed or acted upon as individualized investment advice. It should not be considered a recommendation or solicitation. Information is subject to change. Any forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. The information in this material is not intended as tax or legal advice.

Investing involves risk. Depending on the different types of investments there may be varying degrees of risk. Socially responsible investing does not guarantee any amount of success. Clients and prospective clients should be prepared to bear investment loss including loss of original principal. Indices mentioned are unmanaged and cannot be invested into directly. Past performance is not a guarantee of future results.

The Dow Jones Industrial Average (DJIA) is a price-weighted index composed of 30 widely traded blue-chip U.S. common stocks. The S&P 500 is a market-cap weighted index composed of the common stocks of 500 leading companies in leading industries of the U.S. economy. The NASDAQ Composite Index is a market-value weighted index of all common stocks listed on the NASDAQ stock exchange.

Securities offered through Cambridge Investment Research, Inc., a broker-dealer, member FINRA/SIPC, and investment advisory services offered through Cambridge Investment Research Advisors, Inc., a Registered Investment Adviser. Both are wholly-owned subsidiaries of Cambridge Investment Group, Inc. V.CIR.0926-3518

Market Commentary | September 14th, 2026

Weekly Market Commentary

September 14th, 2026

Week in Review

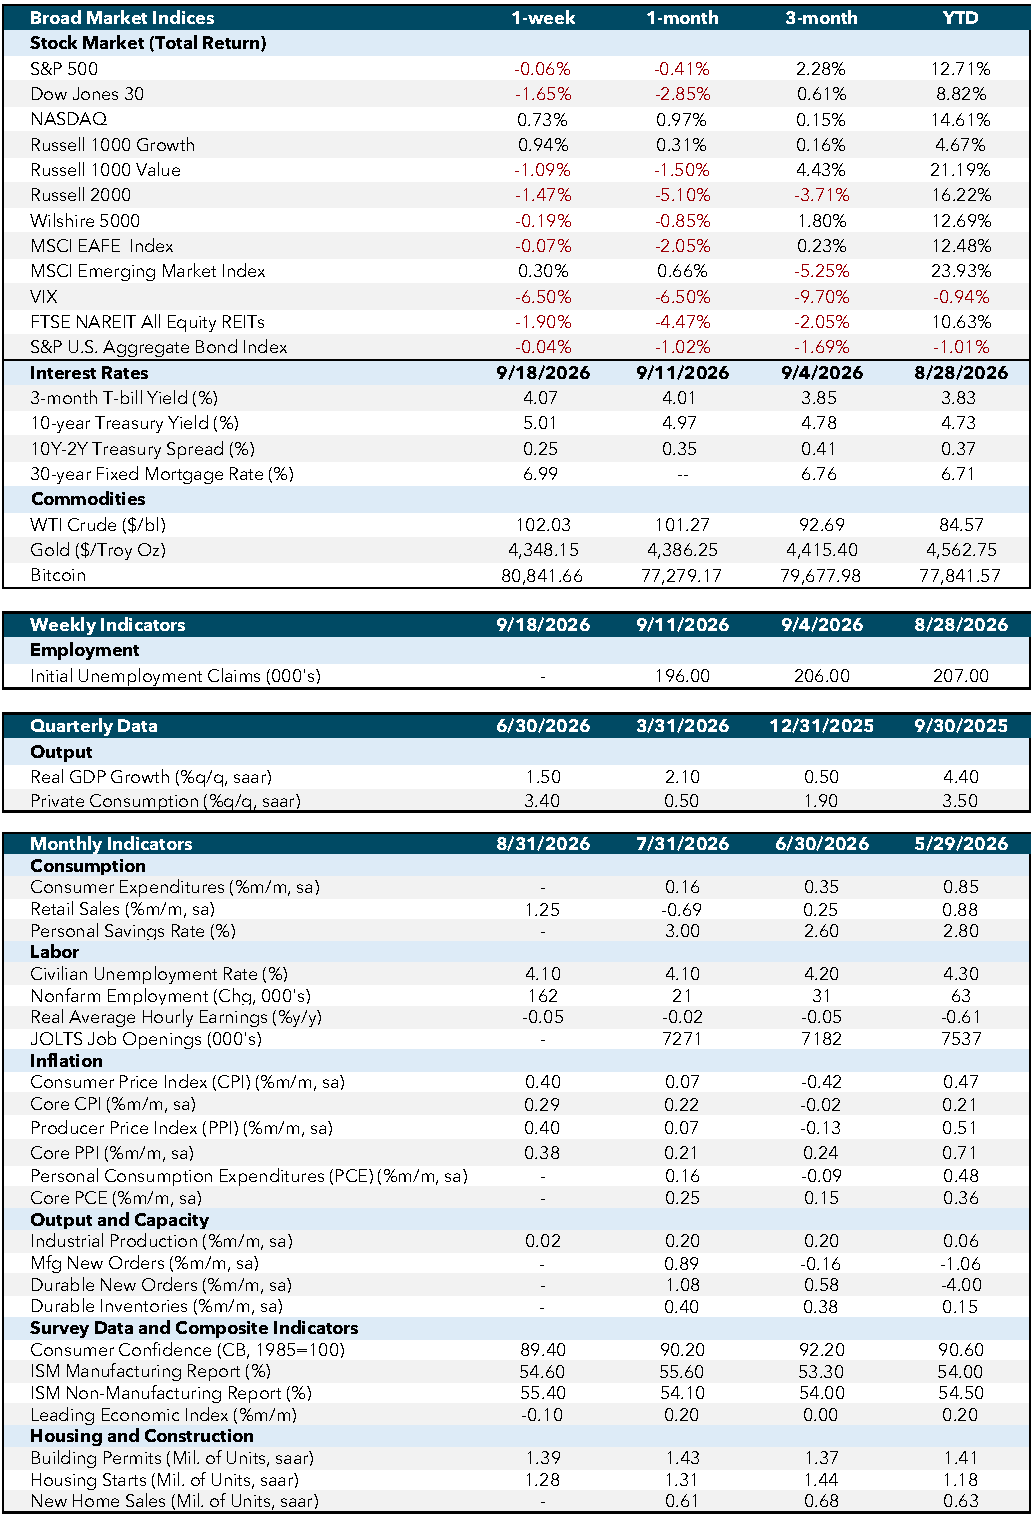
The economic data last week continued to show a U.S. economy that remains resilient, but with inflation pressures moving back into focus ahead of the September Federal Open Market Committee (FOMC) meeting. Treasury yields moved sharply higher over the week, with the 10-year finishing around 4.97%, up from roughly 4.78% the prior Friday, while the 30-year ended near 5.38%, reaching its highest level in nearly two decades.

Despite the rise in yields, demand at both long-duration Treasury auctions was strong. Wednesday’s $39 billion 10-year note auction cleared at 4.834%, the highest auction yield since 2007, but generated a strong 2.71 bid-to-cover ratio. The bid-to-cover ratio measures the amount investors bid relative to the amount of Treasury debt offered, with a higher ratio generally indicating stronger demand. Indirect bidders took roughly 79% of the issue and primary dealers were left with only about 4%, further indicating healthy underlying demand. Thursday’s $22 billion 30-year bond auction was similarly strong, clearing at 5.308% with a bid-to-cover ratio around 2.6. Dealers absorbed just 2.2% of the issue, another indication that investors were willing to add duration at these higher yield levels.

On the economic front, Thursday’s Producer Price Index (PPI) report showed producer prices rising 0.4% month-over-month and 5.4% year-over-year in August. Goods prices rose 1.1%, while services increased just 0.1%, showing that much of the latest inflation pressure is concentrated in goods and energy-related categories. Existing-home sales fell 2.0% to a 3.98 million annualized pace, the lowest level in 14 months, while inventory increased to 1.62 million homes. Housing therefore remains one of the clearer areas where elevated borrowing costs continue to weigh on activity.

Wednesday’s crude-oil inventory report showed commercial crude inventories falling only about 391,000 barrels to 424.1 million, while U.S. production reached a record 13.9 million barrels per day. Gasoline and distillate inventories both increased. Friday’s Consumer Price Index (CPI) report was the most important release of the week. Headline CPI rose 0.4% in August and 3.4% year-over-year, while core CPI increased 0.3% for the month and 2.4% from a year earlier. Gasoline prices rose 3.9%, showing the growing impact of the recent energy-price increase, while the firmer core monthly reading suggested that inflation pressures were not limited entirely to energy.

Economic and Capital Markets Dashboard

Week Ahead…

The first major release this week will be August retail sales on Wednesday morning, just hours before the Fed decision. Retail sales fell 0.6% in July, their first decline in nine months, so August’s report will be important in determining whether consumer spending has rebounded or whether higher prices and softer confidence are beginning to restrain demand.

The primary focus, however, will be the September FOMC meeting on Tuesday and Wednesday, with the policy decision being released Wednesday afternoon. This meeting is particularly highly anticipated because the Fed appears to be approaching an important shift in policy. At the July meeting, the Committee held the federal funds target at 3.50%-3.75%, but the decision was already unusually divided, with three members voting for a 25-basis-point hike. Since then, the Fed has received a strong August employment report, higher-than-expected PPI, a firmer monthly CPI reading, and another sharp increase in energy prices. Markets have consequently moved from viewing a September hike as a close call to pricing roughly an 85% probability of a 25-basis-point increase.

The meeting is also important because September includes an updated Summary of Economic Projections and dot plot. Investors will therefore be looking beyond the immediate rate decision to see how policymakers have changed their forecasts for inflation, growth, unemployment, and the appropriate path for interest rates. The central question is whether the Fed views the recent inflation pressure, particularly from energy, as temporary, or whether the combination of persistent inflation and a still-resilient labor market warrants a broader return to tighter monetary policy. With inflation still materially above the Fed’s 2% objective and three policymakers already favoring a hike at the previous meeting, Wednesday’s decision and updated projections should provide the clearest indication yet of how the Fed intends to navigate the remainder of the year.

Economic Indicators:

  1. CPI: Consumer Price Index measures the average change in prices paid by consumers for goods and services over time. Source: Bureau of Labor Statistics.
  2. Core CPI: Core Consumer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  3. PPI: Producer Price Index measures the average change in selling prices received by domestic producers for their output. Source: Bureau of Labor Statistics.
  4. Core PPI: Core Producer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
  5. PCE: Personal Consumption Expenditures measure the average change in prices paid by consumers for goods and services. Source: Bureau of Economic Analysis.
  6. Core PCE: Core Personal Consumption Expenditures exclude food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Economic Analysis.
  7. Industrial Production: Measures the output of the industrial sector, including manufacturing, mining, and utilities. Source: Federal Reserve.
  8. Mfg New Orders: Measures the value of new orders placed with manufacturers for durable and non-durable goods. Source: Census Bureau.
  9. Durable New Orders: Measures the value of new orders placed with manufacturers of durable goods. Source: Census Bureau.
  10. Durable Inventories: Measures the value of inventories held by manufacturers for durable goods. Source: Census Bureau.
  11. Consumer Confidence (CB, 1985=100): Measures the degree of optimism that consumers feel about the overall state of the economy and their personal financial situation. Source: Conference Board.
  12. ISM Manufacturing Report: Measures the economic health of the manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  13. ISM Non-Manufacturing Report: Measures the economic health of the non-manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
  14. Leading Economic Index: Measures overall economic activity and predicts future economic trends. Source: Conference Board.
  15. Building Permits (Mil. of Units, saar): Measures the number of new residential building permits issued. Source: Census Bureau.
  16. Housing Starts (Mil. of Units, saar): Measures the number of new residential construction projects that have begun. Source: Census Bureau.
  17. New Home Sales (Mil. of Units, saar): Measures the number of newly constructed homes sold. Source: Census Bureau.
  18. SA: Seasonally adjusted.
  19. SAAR: Seasonally adjusted annual rate.

Market Indices & Indicators:

  1. S&P 500: A market-capitalization-weighted index of 500 leading publicly traded companies in the U.S., widely regarded as one of the best gauges of large U.S. stocks and the stock market overall.
  2. Dow Jones 30: Also known as the Dow Jones Industrial Average, it tracks the share price performance of 30 large, publicly traded U.S. companies, serving as a barometer of the stock market and economy.
  3. NASDAQ: The world’s first electronic stock exchange, primarily listing technology giants and operating 29 markets globally.
  4. Russell 1000 Growth: Measures the performance of large-cap growth segment of the U.S. equity universe, including companies with higher price-to-book ratios and growth metrics.
  5. Russell 1000 Value: Measures the performance of large-cap value segment of the U.S. equity universe, including companies with lower price-to-book ratios and growth metrics.
  6. Russell 2000: A market index composed of 2,000 small-cap companies, widely used as a benchmark for small-cap mutual funds.
  7. Wilshire 5000: A market-capitalization-weighted index capturing the performance of all American stocks actively traded in the U.S., representing the broadest measure of the U.S. stock market.
  8. MSCI EAFE Index: An equity index capturing large and mid-cap representation across developed markets countries around the world, excluding the U.S. and Canada.
  9. MSCI Emerging Market Index: Captures large and mid-cap representation across emerging markets countries, covering approximately 85% of the free float-adjusted market capitalization in each country.
  10. VIX: The CBOE Volatility Index measures the market’s expectations for volatility over the coming 30 days, often referred to as the “fear gauge.”
  11. FTSE NAREIT All Equity REITs: Measures the performance of all publicly traded equity real estate investment trusts (REITs) listed in the U.S., excluding mortgage REITs.
  12. S&P U.S. Aggregate Bond Index: Represents the performance of the U.S. investment-grade bond market, including government, corporate, mortgage-backed, and asset-backed securities.
  13. 3-Month T-bill Yield (%): The yield on U.S. Treasury bills with a maturity of three months, reflecting short-term interest rates.
  14. 10-Year Treasury Yield (%): The yield on U.S. Treasury bonds with a maturity of ten years, reflecting long-term interest rates.
  15. 10Y-2Y Treasury Spread (%): The difference between the yields on 10-year and 2-year U.S. Treasury bonds, often used as an indicator of economic expectations.
  16. WTI Crude ($/bl): The price per barrel of West Texas Intermediate crude oil, a benchmark for U.S. oil prices.
  17. Gold ($/Troy Oz): The price per troy ounce of gold, a standard measure for gold prices.
  18. Bitcoin: A decentralized digital currency without a central bank or single administrator, which can be sent from user to user on the peer-to-peer bitcoin network.

This content was developed by Cambridge from sources believed to be reliable. This content is provided for informational purposes only and should not be construed or acted upon as individualized investment advice. It should not be considered a recommendation or solicitation. Information is subject to change. Any forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. The information in this material is not intended as tax or legal advice.

Investing involves risk. Depending on the different types of investments there may be varying degrees of risk. Socially responsible investing does not guarantee any amount of success. Clients and prospective clients should be prepared to bear investment loss including loss of original principal. Indices mentioned are unmanaged and cannot be invested into directly. Past performance is not a guarantee of future results.

The Dow Jones Industrial Average (DJIA) is a price-weighted index composed of 30 widely traded blue-chip U.S. common stocks. The S&P 500 is a market-cap weighted index composed of the common stocks of 500 leading companies in leading industries of the U.S. economy. The NASDAQ Composite Index is a market-value weighted index of all common stocks listed on the NASDAQ stock exchange.

Securities offered through Cambridge Investment Research, Inc., a broker-dealer, member FINRA/SIPC, and investment advisory services offered through Cambridge Investment Research Advisors, Inc., a Registered Investment Adviser. Both are wholly-owned subsidiaries of Cambridge Investment Group, Inc. V.CIR.0926-3452